Why is ATOM up by more than 12% in the last 24 hours?

ATOM is one of the best performers amongst the top 30 cryptocurrencies by market cap today. 

ATOM, the native token of the Cosmos ecosystem, is one of the best performers amongst the top 30 cryptocurrencies by market cap today. The coin has added more than 12% to its value today, outperforming the broader crypto market. 

The cryptocurrency market is slowly recovering today, following a slow start to the week. After losing more than 3% of its value yesterday, the crypto market is up by nearly 2% so far today. 

The positive performance has pushed the total cryptocurrency market cap above the $1 trillion mark again.

Bitcoin remains above the $21k level and could rally higher today after adding more than 1% to its value. Ether is trading above $1,600 after depending its price above the $1,500 psychological level yesterday. 

However, ATOM is the second-best performer amongst the top 30 cryptocurrencies by market cap (only behind Bitcoin Cash).

There is no catalyst behind ATOM’s ongoing rally as it could be only a recovery from its recent price crash. Despite adding more than 12% to its value today, ATOM is down by 1% in the last seven days.

Key levels to watch

The ATOM/USD 4-hour chart has turned bullish as Cosmos has been performing well over the past 24 hours. 
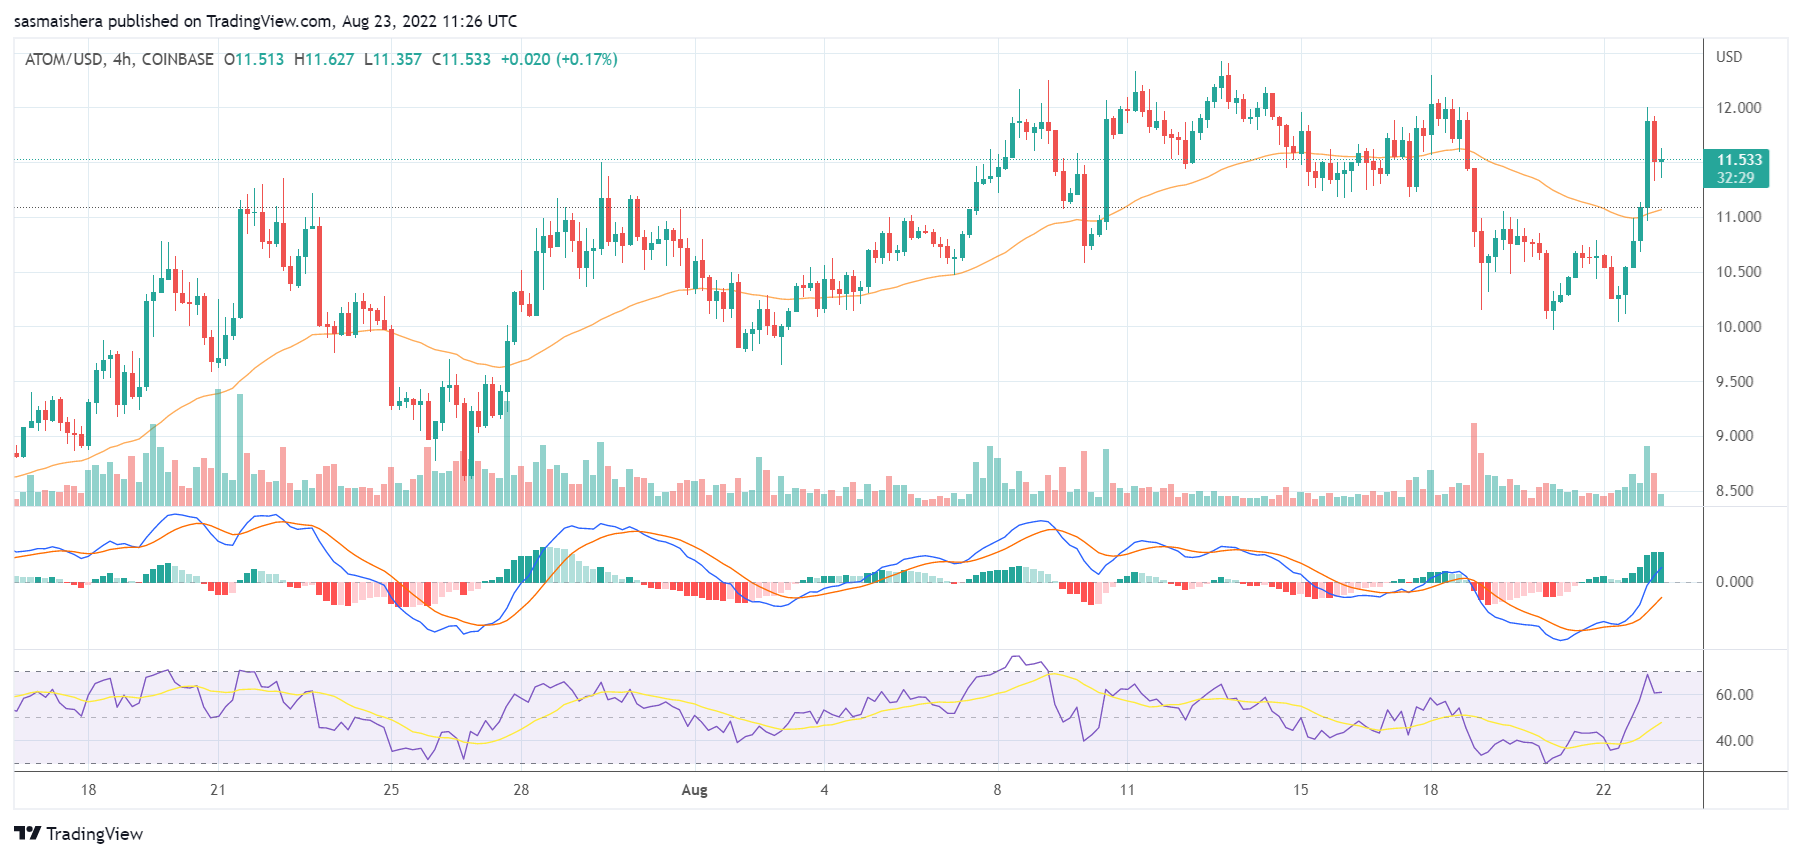
The MACD line crossed into the positive zone a few hours ago, indicating that ATOM is no longer bearish.

The 14-day relative strength index of 60 shows that ATOM could enter the overbought region if the positive momentum continues. 

At press time, ATOM is trading at $11.52. If the positive momentum continues, ATOM could move past the first major resistance level at $12.271 before the end of the day. 

However, ATOM would need the support of the broader market to reach the $13.60 mark for the first time since May.

The post Why is ATOM up by more than 12% in the last 24 hours? appeared first on CoinJournal.
Bitcoin eyes the $22k resistance level as the market slowly recovers

Bitcoin could rally towards the $22k resistance level over the coming hours as the broader market slowly recovers.

The cryptocurrency market is slowly recovering today, following a slow start to the week. After losing more than 3% of its value on Monday, the crypto market is up by nearly 2% in the last 24 hours. 

The positive performance has pushed the total cryptocurrency market cap above the $1 trillion mark again.

Bitcoin nearly dropped below the $21k support level on Monday but has maintained its value above that threshold. Bitcoin is now trading around $21,400 per coin and could make a move for the $22k resistance level over the next few hours if the market momentum is maintained.

Bitcoin reaching the $25k psychological level in the near term would depend on the sentiment in the broader cryptocurrency market. 

Key levels to watch

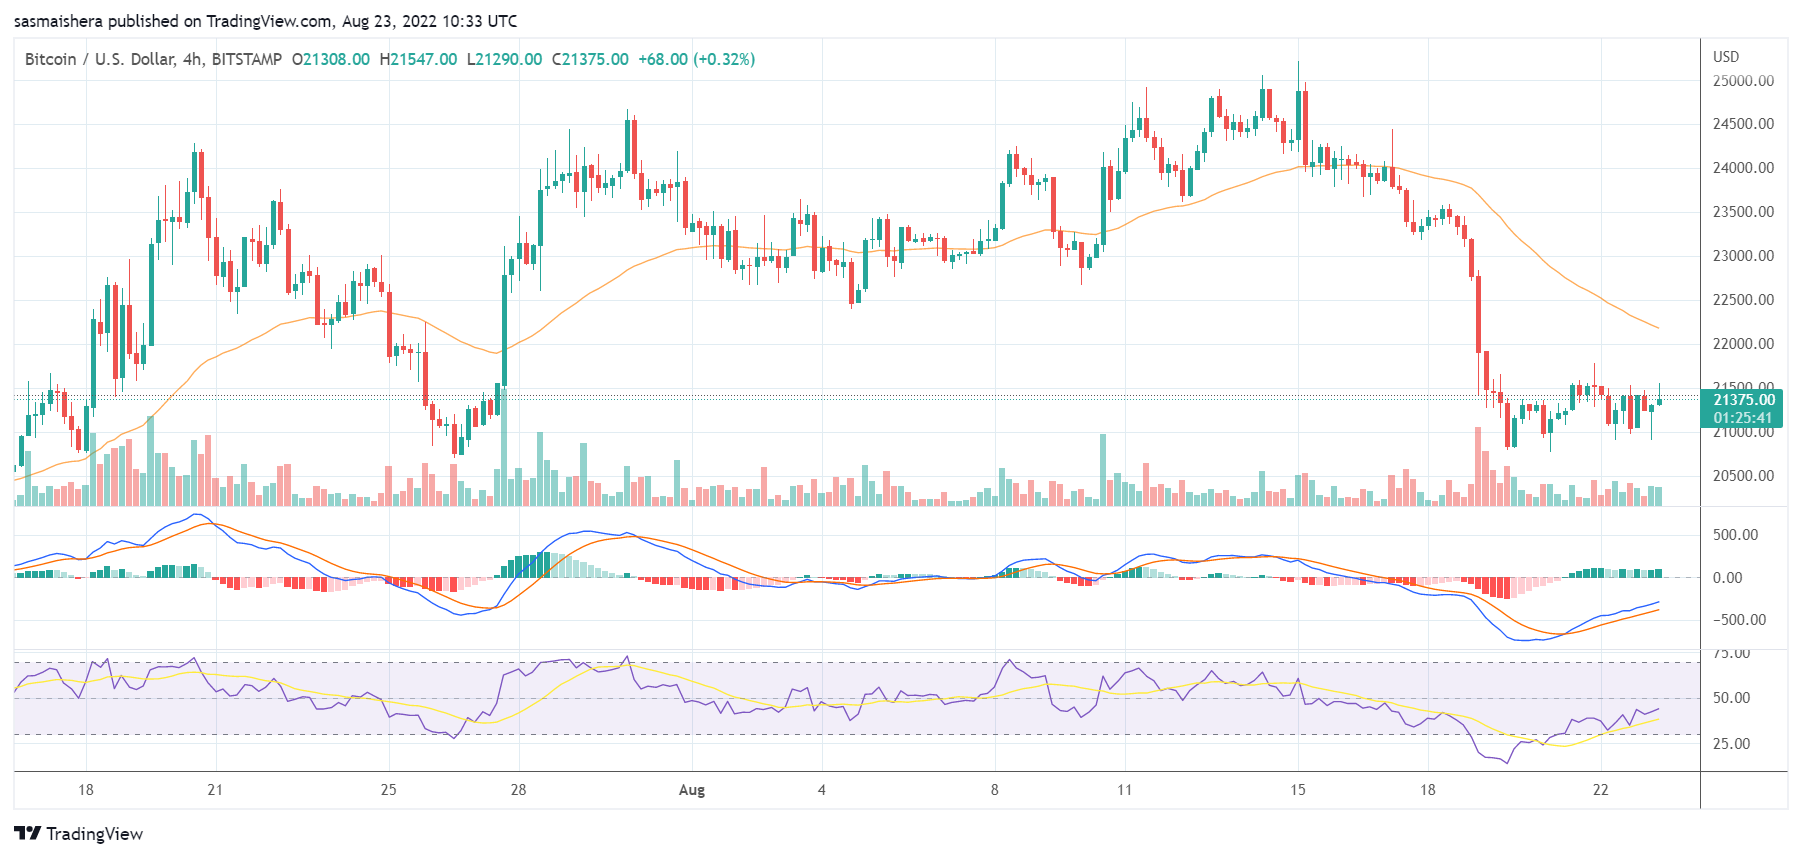
The BTC/USD 4-hour chart remains bearish despite Bitcoin adding 1% to its value in the last 24 hours. The technical indicators show that Bitcoin’s performance is improving, but it is yet to be bullish.

The MACD line dropped into the negative zone on August 16 and has remained there. Thus, indicating that the bearish trend for Bitcoin is not yet over.

The 14-day relative strength index of 44 shows that Bitcoin is no longer in the oversold region. However, it is still some way from entering the overbought zone of the chart.

At press time, BTC is trading at $21,360 per coin. If the market recovery continues, BTC could surpass the $22,724 resistance level over the next few hours or days.

However, Bitcoin could find it hard to reach the second major resistance level at $23,960 in the near term unless there is a bullish movement.

The bears are still lurking and could regain control of the market. Doing so would see BTC fall below the $21k support level for the second time in less than a week. 

Bitcoin has maintained its value above $20k and should comfortably do so over the next few days.

The post Bitcoin eyes the $22k resistance level as the market slowly recovers appeared first on CoinJournal.

NFT lending protocol Bend DAO proposes emergency actions to stabilize ecosystem

NFTs borrowing and lending protocol Bend DAO is staring at a credit crisis after it was revealed on Monday that the protocol only had about 15 wrapped Ether (wETH) worth about $23,715 for paying back its lenders.  The protocol has so far lent out 15,000 ETH.

To avert the crisis, the project’s developers have proposed new emergency measures aimed at stabilizing Bend DAO’s ecosystem.

The proposed emergency measures 

To start with the development team suggested constraining the liquidation threshold for collateral at 70% of the loan value; cutting it down from 85%.

Secondly, the auction period for NFTs would be reduced from 48 hours to four hours and the requirement for the minimum bid price of NFTs to be pegged to 95% of the floor price on OpenSea would be scrapped.

Thirdly, interest rates on loans shall rest from the current 100% to 20%.

Lastly, the Bend DAO treasury shall be empowered to cover all the bad debts using revenue.

What led to the current Bend DAO situation?

Generally, the declining floor prices of NFTs in the market even among popular NFT collections is placing many NFTs in danger of being liquidated. The interest rates on “debt-secured” NFTs are skyrocketing and it has almost hit 100% making some users prefer letting go of their NFTs rather than paying back the debt and this is resulting in a lot of bad loans. Also, the NFT markets are not as liquid as coin markets meaning there may not be a single bid at the time of an NFT liquidation; something that further complicates the scenario.

The proposal by Bend DAO is currently being voted for by the community. The voting process is expected to last 24 hours although it has already passed the required 47 million veBend with 99.23% of voters in favour of the proposal.

The post NFT lending protocol Bend DAO proposes emergency actions to stabilize ecosystem appeared first on CoinJournal.

Telegram founder proposes NFT marketplace for auctioning popular usernames

Telegram founder Pavel Durov is proposing the creation of an NFT marketplace that can use “NFT-like smart contracts” to facilitate auctioning of popular usernames.

Durov’s proposal comes after the success of domain name auctions on The Open Network (TON), which is a layer-1 blockchain designed by the Telegram team. The Open Network launched the TON DNS Service in mid-July allowing users to assign human-readable names to crypto wallets, websites, and smart contracts.

Durov through a message shared on his personal Telegram group, Durov’s Channel, on Tuesday said that he was impressed by the success of the domain auctions on TON. He said that Telegram could tap into the same technology and launch a new marketplace that would be used to buy and sell “catchy t.me addresses like @storm or @royal, and all four-letter user names.”

Durov said:

“Imagine how successful Telegram with its 700 million users could be it we put reserved @ usernames, group and channel links for auction… This would create a new platform where username holders could transfer them to interested parties in protected deals – with ownership secured on the blockchain via NFT-like smart contracts.”

Auctions on TON DNS Service

The first auction on TON DNS was conducted on July 30 and just like the Ethereum Name Service (ENS) “.eth” domains, the “.ton” domains allow users to access decentralized applications in a simpler way without needing to write the long crypto wallet addresses.

The Open Network uses FunC programming language for the TON Virtual Machine and to launch specific smart contracts on the blockchain. If Telegram was to launch NFTs, it would most likely use the same standard.

Durov said:

“Our team can write bullet-proof smart contracts for TON (since it was us who invented its smart contract language), so we are inclined to try out TON as the underlying blockchain for our future marketplace.” 

The post Telegram founder proposes NFT marketplace for auctioning popular usernames appeared first on CoinJournal.

Acala community okays burning billions of erroneously minted aUSD stablecoin

According to a news post by the co-founder of Acala Network, Bette Chen, the Acala community has voted to burn 2.97 billion Acala USD (aUSD) stablecoins.

Acala is a scalable and Ethereum-compatible layer-1 smart contract platform built on Polkadot blockchain and it is the blockchain network that powers the aUSD stablecoin.

The aUSD stablecoin

aUSD is over-collateralized by several digital assets from the Kusama network and Polkadot ecosystem, with a deposit rate of 195% per every minted aUSD.

aUSD de-pegging

Last week, the price of aUSD de-pegged from its US dollar peg and dropped to below $0.01. The cause for the de-pegging was later found to be a sudden influx of the aUSD stablecoin supply caused by an erroneous minting.

3.022 billion aUSD stablecoins were erroneously minted after the iBTC/aUSD liquidity pool that went live on August 14 was misconfigured.

The misconfiguration has however since been rectified and the wallet addresses that benefited from the erroneously minted aUSD identified through on-chain tracing. Thirty-five accounts were found to have received 12.38 million aUSD.

More than 99% of the erroneously minted aUSD were then transferred to the Acala parachain. But some, approximately worth $9.69 million, had been swapped to DOT and moved to centralized crypto exchanges.

The aUSD is currently trading at about $0.84 which is still below its dollar parity; meaning the erroneous minting is still affecting the system’s equilibrium.

The post Acala community okays burning billions of erroneously minted aUSD stablecoin appeared first on CoinJournal.