
Coinbase fined for operating in the Netherlands: here’s why

  • Dutch Central Bank announces a $3.6 million fine on Coinbase.
  • It says the crypto exchange has been in a regulatory violation.
  • Shares of Coinbase Global Inc ended roughly flat on Thursday.

Coinbase Global Inc seems to be up for another regulatory fine.

On Thursday, the Dutch Central Bank forced a $3.60 million penalty on the cryptocurrency exchange for failing to comply with the domestic regulations.

What regulation did Coinbase not comply with?

In May 2020, Netherlands made it mandatory for businesses wanting to launch crypto-related services to register with the DNB first.

But Coinbase, as per the central bank, did not go through such a registration and, therefore, was in regulatory violation for nearly two years; between November 2020 and August 2022. The DNB said:

Coinbase has enjoyed a competitive advantage in that it has not paid any supervisory fees to DNB or incurred other costs in connection with DNB’s regular supervision activities.

Last year, the regulator had hit its peer Binance with a $3.35 million fine as well.

Coinbase recently settled with the NYDFS as well

According to the Dutch Central Bank, the said non-compliance might have made the Financial Intelligence Unit miss a bunch of suspicious transactions through September of 2022.

Nonetheless, Coinbase can appeal the penalty until March 2nd. Earlier in January, it signed a $100 million settlement with the New York Department of Financial Services (NYDFS) as well.

A day earlier, Mizuho analyst Dan Dolev warned of a potential 40% downside in Coinbase stock (as Coin Journal reported HERE) that ended roughly flat on Thursday.

Analysts expect the crypto company to report a $2.39 per share loss in its current quarter. A year ago, it had $3.32 of EPS instead.

The post Coinbase fined for operating in the Netherlands: here’s why appeared first on CoinJournal.
SEC rejects Ark 21Shares’ spot Bitcoin ETF again

  • SEC has denied the Ark Investment and 21 Shares joint spot Bitcoin ETF application.
  • The agency says proposal failed to meet requirements as per securities laws, citing fraud and manipulative practices once again.
  • It’s the second time the SEC has rejected an ETF proposal by the two firms, after denying the first one in April last year.

The US Securities and Exchange Commission (SEC) has disapproved a proposal seeking to list a spot Bitcoin exchange-traded fund (ETF) for the US market.

In a document published on Thursday, the US securities market watchdog said it had rejected the application by Cathie Wood’s Ark Investment and Swiss cryptocurrency investment firm 21Shares. 

The Ark 21Shares spot Bitcoin ETF had been proposed for listing on the Cboe BZX Exchange.

SEC denies Ark 21 Shares Bitcoin ETF again

The Commission’s order disapproving the two companies’ ETF application noted that BZX did not “demonstrate that its proposal is consistent with the requirements of Exchange Act Section 6(b)(5).” 

Specifically, the exchange failed to demonstrate that it could prevent fraud and other manipulative practices as well as protect those looking to invest in the product.

“The Commission further concludes that BZX has not established that it has a comprehensive surveillance-sharing agreement with a regulated market of significant size related to spot bitcoin, the underlying bitcoin assets that would be held by the Trust,” reads part of the SEC’s reasoning for disapproval.

This is the second time the agency has rejected a spot Bitcoin ETF proposal by Ark Investment Management and 21Shares. The SEC dismissed a similar application in April, a move that prompted the two firms to submit a fresh one last May.

The SEC has also disapproved of multiple other spot bitcoin ETF applications, including one by Grayscale Investment, which sought to convert the Grayscale Bitcoin Trust (GBTC) to a BTC spot ETF. The asset manager filed a lawsuit against the agency following the agency’s move in June 2022. 

The post SEC rejects Ark 21Shares’ spot Bitcoin ETF again appeared first on CoinJournal.

Toncoin (TON) options goes live on Bitcoin exchange BIT

  • Toncoin (TON) options went live on the crypto derivatives exchange BIT on Thursday, 26 January.
  • TON is now the third cryptocurrency available for options trading on BIT, adding to Bitcoin and Ethereum.
  • The options product will also go live on institutional liquidity network Paradigm in early February.

Crypto derivatives exchange BIT has launched options trading for Toncoin (TON), the cryptocurrency native to The Open Network (TON) ecosystem. 

Options, which is a contract that allows a trader the right to buy or sell an asset, is one of the most popular crypto derivatives products in the market.

According to details shared with CoinJournal via a press release on Thursday, trading options for the digital token will also go live on Paradigm in early February. Paradigm is a leading institutional-focused derivatives liquidity network.

BIT adds TON to product suite

Until BIT’s launch of the TON options trading, market participants could only access options pegged on the world’s two largest cryptocurrencies by market cap – Bitcoin (BTC) and Ethereum (ETH).

The product is a result of a partnership between BIT, leading crypto market maker DWF Labs and liquidity provider Darley Technologies,, the BIT team noted in the press release.

According to the derivatives exchange, the launch of Toncoin options could see the digital token attract more institutional investors and other big money players, offering a low-risk avenue for this group of investors to gain exposure to the market.

Data from CoinGecko shows that TON ranks 23rd among the largest cryptocurrencies by market cap. At the time of writing, the Toncoin market cap stood at around $3.5 billion, with the price of TON token changing hands near $2.38 and up 6.4% in the past 24 hours.

The post Toncoin (TON) options goes live on Bitcoin exchange BIT appeared first on CoinJournal.

Porsche NFT price suddenly soars days after mint halt: here’s why

  • The first-ever Porsche (Cayman S) was sold for 300 BTC back in 2013.
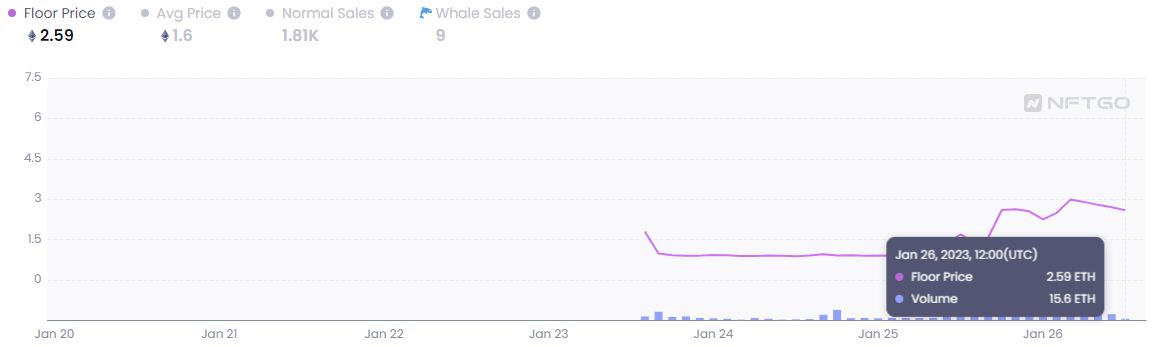
  • At press time, Porsche 911 NFT floor price was 2.59 ETH.
  • Initially, a total of 7,500 Porsche 911 NFTs were to be minted before the motor company abruptly halted the minting process.

Day after Porsche halted the Porsche 911 NFT minting, the floor price shot up to an all-time high of 2.9 ETH before pulling back to 2.59 ETH, up 52% at press time.

The trading volume of the Porsche NFTs has also gone up by 214% to 1.96K ETH according to data obtained from NFTGO.

Porsche 911 NFTs

Porsche ventured into the NFT space in 2021 by launching an NFT marketplace named Fanzone. The car-making behemoth later announce issuing a series of NFTs planning to have a total of 7,500 NFTs being minted.

However, the NFTs were poorly received by fans forcing the company to halt the mint with only 2,363 NFTs having been minted. And after that, the floor price of the Porsche 911 NFTs shot up by more than four times.

Porsche 911 NFTs floor price. Source NFTGO

Why is the Porsche NFTs price rising?

There is no main reason behind the sudden price pump beside the usual demand and supply metrics.

Going by the increased trading volume shows that more people have become interested in NFTs, something that has undoubtedly caused their prices to shoot up as demand increases. At the same time, the supply remains stagnant after the minting halt.

Although it is not clear how far the Porsche 911 NFTs floor price will climb, there are expectations that the price could quickly get above 3 ETH by the end of the week.

The post Porsche NFT price suddenly soars days after mint halt: here’s why appeared first on CoinJournal.

115-page doc shows big tech firms, airlines and government entities owed by FTX

  • The 115-page document was filed by FTX lawyers in the US Bankruptcy Court for the District of Delaware.
  • The list of creditors shows all those owed money by the collapse FTX crypto exchange.
  • The document however redacts the names of individual customers whose money is stuck in FTX.

A 115-page document (creditor matrix) filed on late January 25 by the lawyers of the collapse FTX crypto exchange has revealed the list of big tech companies, crypto firms, airlines, media outlets, hotels, banks, charities, government entities, venture capital firms, and local businesses near FTX Bahamas headquarters whose money is stuck in FTX.

The document has shocked many since the majority thought that FTX only worked with crypto-based firms and no government entity was involved.

Creditors listed in the document

The document only listed entities but redacted the names of the nearly 9.7 million individual customers whose funds are stuck in the collapsed exchange.

Prominent crypto and web3 companies including entities of Binance, Circle, Galaxy Digital, Bittrex, Coinbase, Yuga Labs, Sky Mavis, Messari, and Chainalysis have been listed in the document

Big tech companies including Meta, Apple, Amazon, Netflix, Google, Microsoft, Twitter, and LinkedIn have been captured in the document and media outlets including New York Times, CoinDesk, and The Wall Street Journal have also been mentioned.

Shockingly according to the document, FTX also owes money to tax offices of several US state agencies and the federal Internal Revenue Service (IRS) in addition to government entities in Australia, Hong Kong, and Japan.

In addition to large companies, FTX also owes funds to a Nassau-based pest control business and a garden centre, FTX’s prior public relations company M Group.

It is however important to note that the entities appearing on the list did not necessarily have a trading account with FTX.

The post 115-page doc shows big tech firms, airlines and government entities owed by FTX appeared first on CoinJournal.