
Crypto’s correlation with stocks rising again following temporary deviation


Key Takeaways

  • Crypto had moved in line with stocks and other risk assets throughout the interest rate tightening cycle
  • This relationship weakened in June amid the crypto regulatory crackdown
  • The correlation has recently picked up again, however
  • Going forward, relationship may change again as the market anticipates the tightening cycle is coming to a close

We know that within the digital asset space, the different cryptocurrencies are highly correlated. As a generalisation, it is fair to say that many altcoins tend to trade like levered bets on Bitcoin. 

Going beyond the asset class and assessing correlations with other asset types becomes more interesting. One of the most intriguing trends to track is the correlation between Bitcoin and stocks. If we want to assess Bitcoin through a macroeconomic lens, its relationship with other asset classes is of vital importance. 

The last eighteen months have thrown this relationship into a new light, as correlations have been extremely high amid one of the fastest interest rate tightening cycles in recent history. With liquidity sucked out of the economy, risk assets were hammered last year, including Bitcoin. 

Compared to the tech-heavy Nasdaq, Bitcoin’s correlation has been persistently high throughout this period, bar a few noticeable instances. As displayed on the below chart from an analysis we compiled six weeks ago, the collapses of Luna, Celsius and FTX saw deviations in this relationship. 

These explain themselves, as dramatic crypto-specific episodes that had no effect on stocks. However, the more recent deviation was bigger than any: coming in June amid the regulatory crackdown (chart is taken from June 15th, a week after the Binance and Coinbase lawsuits). 
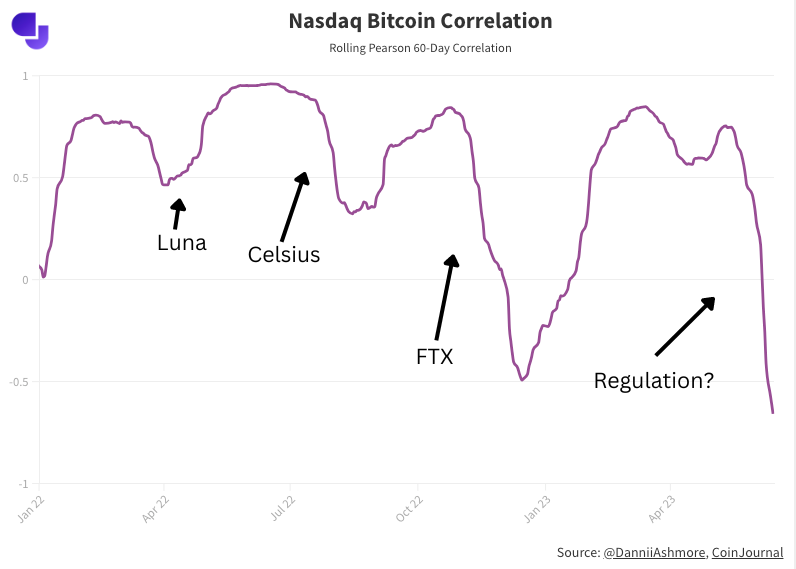
In fact, this deviation brought the Nasdaq’s correlation with Bitcoin to a five-year low. If we now re-run this chart, we see the correlation has picked back up again, rising to 0.5 and trending upwards.


This highlights what we already knew: the deviation is only temporary. It came following a month where the Nasdaq jumped 10% off softer forecasts around the future path of interest rate hikes, while Bitcoin fell 9% over the same time period as lawmakers tightened their squeeze on the industry, suing the two largest exchanges and confirming several tokens constituted securities.  

The climate has picked up for crypto since. Ripple won an important case (or, partially won, but the result was undoubtedly positive for the space), while a slew of spot ETF applications have also served to increase optimism. 

While the deviation was always going to be temporary, going forward in the medium-term, things could get more interesting. This is because, finally, the market is anticipating that the majority of interest rate hikes are in the rearview window, with perhaps only one more still to be endured, if even. 

This could release the shackles which have been around Bitcoin’s ankles, and it remains to be seen how the asset will henceforth move in relation to the stock market. We know that the correlation picked up as soon as the Federal Reserve began hiking interest rates; correlations go to 1 in a crisis, and there is a flight to quality – risk assets suffer in that scenario, and that is exactly what we saw. 

There is every chance that both stocks and Bitcoin will continue to trade in tandem, but if/when this tightening cycle ends, it will at least give the market a fresh opportunity to trade them whilst global liquidity is not being pulled off the table. 

Regardless of the relationship between the duo, the below chart shows just how dependent Bitcoin has been on yields – the two-year treasury yield, plotted on an inverse scale, has moved exceptionally closely with Bitcoin, ever since the latter’s all-time high in November 2021. 

How will Bitcoin’s relationship with gold change?

It is Bitcoin’s relationship with gold that provides an equal amount of intrigue, given the former’s designs on becoming some sort of digital equivalent of the latter. Should Bitcoin become a store of value, it will need to become a little more boring with regard to price movements – something gold is well known for. 

However, correlation between the two assets has dipped, moving in the opposite direction to that of stocks. From rising markedly this year, it has fallen sharply in the last month. 

If Bitcoin is to achieve what so many want to do – become an uncorrelated asset capable of offering a portfolio hedge properties – it must flip the script here. Its relationship with stocks will need to loosen, while it will need to get closer to the way gold trades. 

Having said that, Bitcoin has been around only 14 years, and has traded with reasonable liquidity for far less than that. It is still finding its feet, and it remains early – certainly compared to gold, which has been around for thousands of years. 

The post Crypto’s correlation with stocks rising again following temporary deviation appeared first on CoinJournal.
Chainlink price prediction: Here’s what top analyst says about LINK

  • Chainlink (LINK) traded to highs of $8.44 before retreating amid broader market uncertainty.
  • A top crypto analyst says LINK seeing a weekly close below the macro downtrend line portends fresh losses. 
  • The “Macro Breakout is postponed” the analyst noted on Monday. 

Chainlink posted an impressive run in the week of July 13-21, notching a +20% gain in a single day on July 20 as it hit a three-month high of $8.44. On-chain volume spiked to over $347 million as traders poured into the altcoin amid positive network developments.

Chainlink price analysis

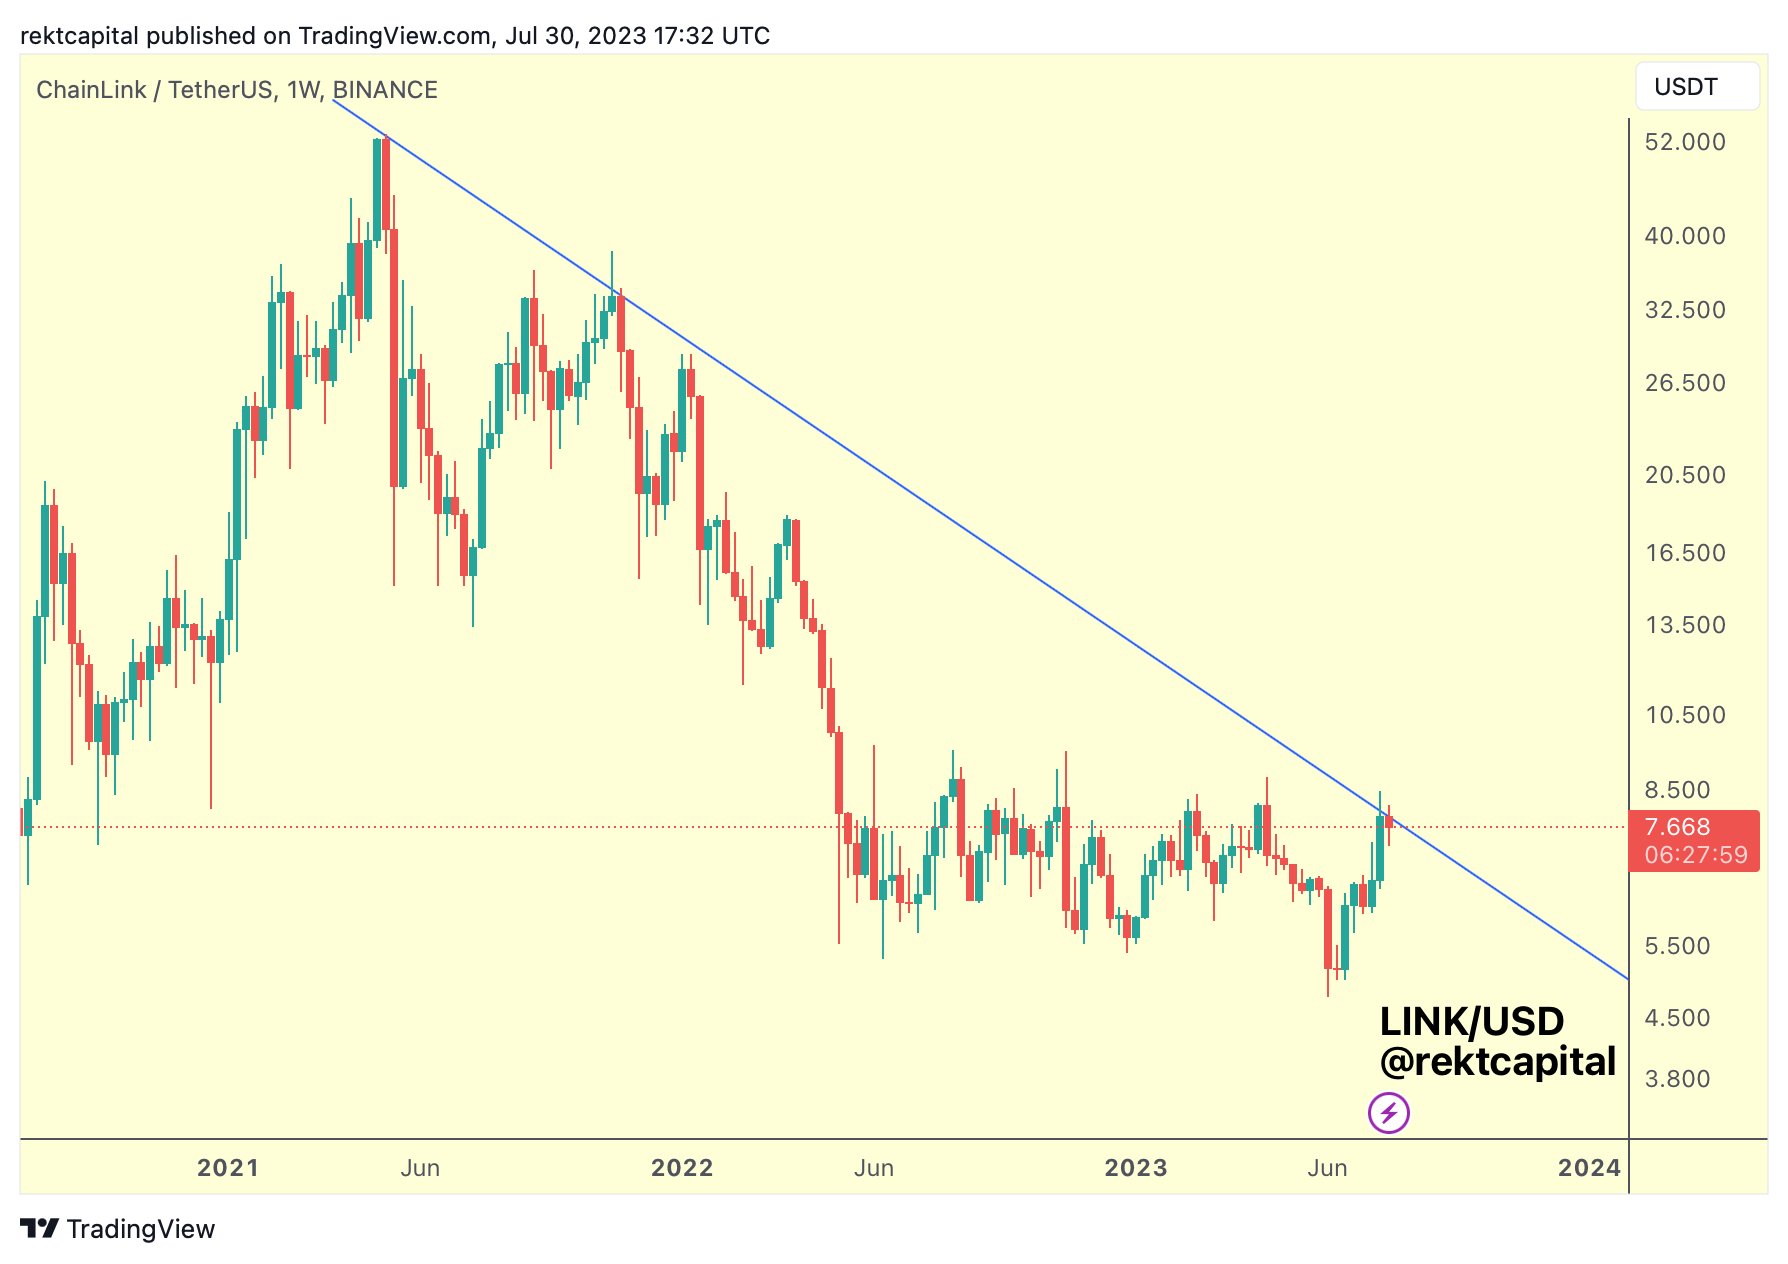
LINK bulls appeared to be on the way to retesting a key technical level just under $10, with price poised to break a multi-year macro downtrend. 

Crypto analyst Rekt Capital highlighted this on Friday, identifying a potential weekly close above the macro downtrend line as a likely indicator of bullish strength.

As can be seen in the chart below, Chainlink price has recoiled from the crucial hurdle with a weekly close below. According to the analyst, the scenario where the would-be macro breakout has fizzled out (at the moment.)

“$LINK has ultimately performed its new Weekly Close below the Macro Downtrend. As a result, the Macro Breakout is postponed. Unless #LINK is able to reclaim this Macro Downtrend as support, price is positioning itself up for a rejection from here,” Rekt Capital shared on X (fka Twitter).

Chainlink weekly price chart showing LINK new weekly close. Source: Rekt Capital.
LINK currently trades near $7.60, largely flat in the past 24 hours. Investors have seen gains recorded over the past week cut to just 1%. LINK/USD is up 20% in the past 30 days.

If prices fall below $7.00, the next major support zone could be around $5.00. On the upside, $8.50 and $10 are key supply zones. 

Here’s something else the analyst points out about Chainlink price performance.

The post Chainlink price prediction: Here’s what top analyst says about LINK appeared first on CoinJournal.

Tether’s excess reserves rose to $3.3B in Q2: report

  • Tether’s excess reserves for the USDT stablecoin hit $3.3 billion in Q2.
  • An attestation report for the quarter by BDO showed operational profits of over $1 billion.
  • Tether’s consolidated liabilities was roughly $83.17 billion, while exposure to US Treasuries totaled $72.5 billion.

Tether Holdings Limited, the company behind the USDT stablecoin, saw its reserve assets held in excess rise to $3.3 billion in Q2, 2023, according to an attestation report for the quarter released on Monday.

The stablecoin issuer’s Consolidated Reserves Report (CRR) for the quarterly period ending June 30, 2023 was prepared by the accounting firm BDO. Per the assurance report, Tether saw its excess reserves increase by $850 million during the quarter to reach $3.3 billion.

As of 30 June 2023, Tether’s consolidated total assets were $86,499,251,218, while consolidated total liabilities stood at $83,200,775,340. According to the company, $83,178,020,411 of this was related to the digital tokens it has issued.

With USDT the firm’s largest token, total US Treasuries backing USDT by end of Q2 was $72.5 billion, details shared in the report showed.

“I am immensely proud of our most recent reserves attestation, reaffirming our unwavering commitment to transparency,” Tether CTO Paolo Ardoino said.

“Transparency is not just a buzzword for us; it is the cornerstone of our philosophy. We believe that open communication and strong financials foster trust and reliability, and this is what the global community deserves especially in a year devastated by many failures across the banking and crypto industry.”

Tether also revealed operational profits of over $1 billion for the quarter, signaling a 30% increase in operational profits QoQ. The impressive returns come after the company announced net profits of $1.45 billion in Q1, 2023.

The post Tether’s excess reserves rose to $3.3B in Q2: report appeared first on CoinJournal.

Hex founder charged with offering unregistered securities offering

  • Richard Heart was charged with allegedly raising over $1B through unregistered securities offerings.
  • The SEC also charged PulseChain, PulseX, and Hex, alongside Richard Heart.
  • In addition, Heart and PulseChain have also been charged for using part of the offering proceeds to buy luxury goods.

The US Securities and Exchanges Commission (SEC) has charged the founder of the crypto project Hex, Richard Heart, with allegedly raising more than $1 billion through unregistered securities offerings. The SEC has also included three unincorporated businesses (PulseChain, PulseX, and Hex) in the charges.

PulseChain and Richard Heart are also both facing charges for purportedly using $12 million from the funds raised through the securities offerings to buy luxury goods, including a 555-carat black diamond christened “The Enigma.”

Details of SEC’s charges against Hex

The SEC’s lawsuit has been filed in the United States District Court for the Eastern District of New York.

The SEC complaint states that the HEX founder started marketing Hex in 2018 claiming that “it was the first high-yield ‘blockchain certificate of deposit,” and started endorsing Hex tokens as an investment designed to make people “rich.”

The SEC is particularly wary of a staking function on Hex that Heart claimed would provide returns of 38% and claims that Heart intentionally tried to break the law by advising Hex investors to “sacrifice” their cryptocurrency holdings rather than invest in them.

Director of the Fort Worth regional office, Eric Werner, also weighed into the matter saying that Heart urged investors to purchase securities backed by cryptocurrency in offerings that he neglected to register and then went ahead to use some of the cryptocurrency assets to purchase extravagant luxury items.

HEX price reaction

The price of the HEX token had dipped by more than 27% to trade at $0.006461 at press time following the news of the charges.

The Hex charge came as the SEC also asked Coinbase to only offer Bitcoin (BTC) stating that all the other cryptocurrencies are securities.

The post Hex founder charged with offering unregistered securities offering appeared first on CoinJournal.

Bitcoin volatility at three-year low as crypto markets lull


Key Takeaways

  • Crypto volatility has been dropping all year, with Bitcoin’s volatility now at three-year lows
  • Volume is also dropping, as the calm markets are not welcomed by traders
  • Despite downward-trending volatility, crypto remains highly volatile when compared to other asset classes

Crypto markets are known for violent volatility, capable of both spiking and collapsing in the blink of an eye. 

Thus far this year, however, that hasn’t been the case. Volatility has been trickling steadily downward across the space. Assessing the realised volatility of Bitcoin over a rolling one-month window, the metric is currently at a three-year low. 

This comes despite Bitcoin having had a bumper year thus far, the asset currently up 76%, treading water around the $30,000 mark. In the past, Bitcoin has oscillated wildly, but this run-up from the low of $15,500 late last year has been distinguished by a steady climb rather than the turbulent ups and downs we have come to expect. 

The pattern is not unique to the world’s biggest crypto, either – volatility is falling across the board. The easy way to illustrate this is by looking at Ether. Historically, the price of ETH has been more volatile than BTC, but the divergence has narrowed this year, and Ether is now trading with similar volatility to its big brother. 

This relative calm in crypto markets is good on one level, given one of Bitcoin’s most-cited criticisms is its extreme volatility, which most agree it will need to overcome should it ever take the status of a reputable store of value. 

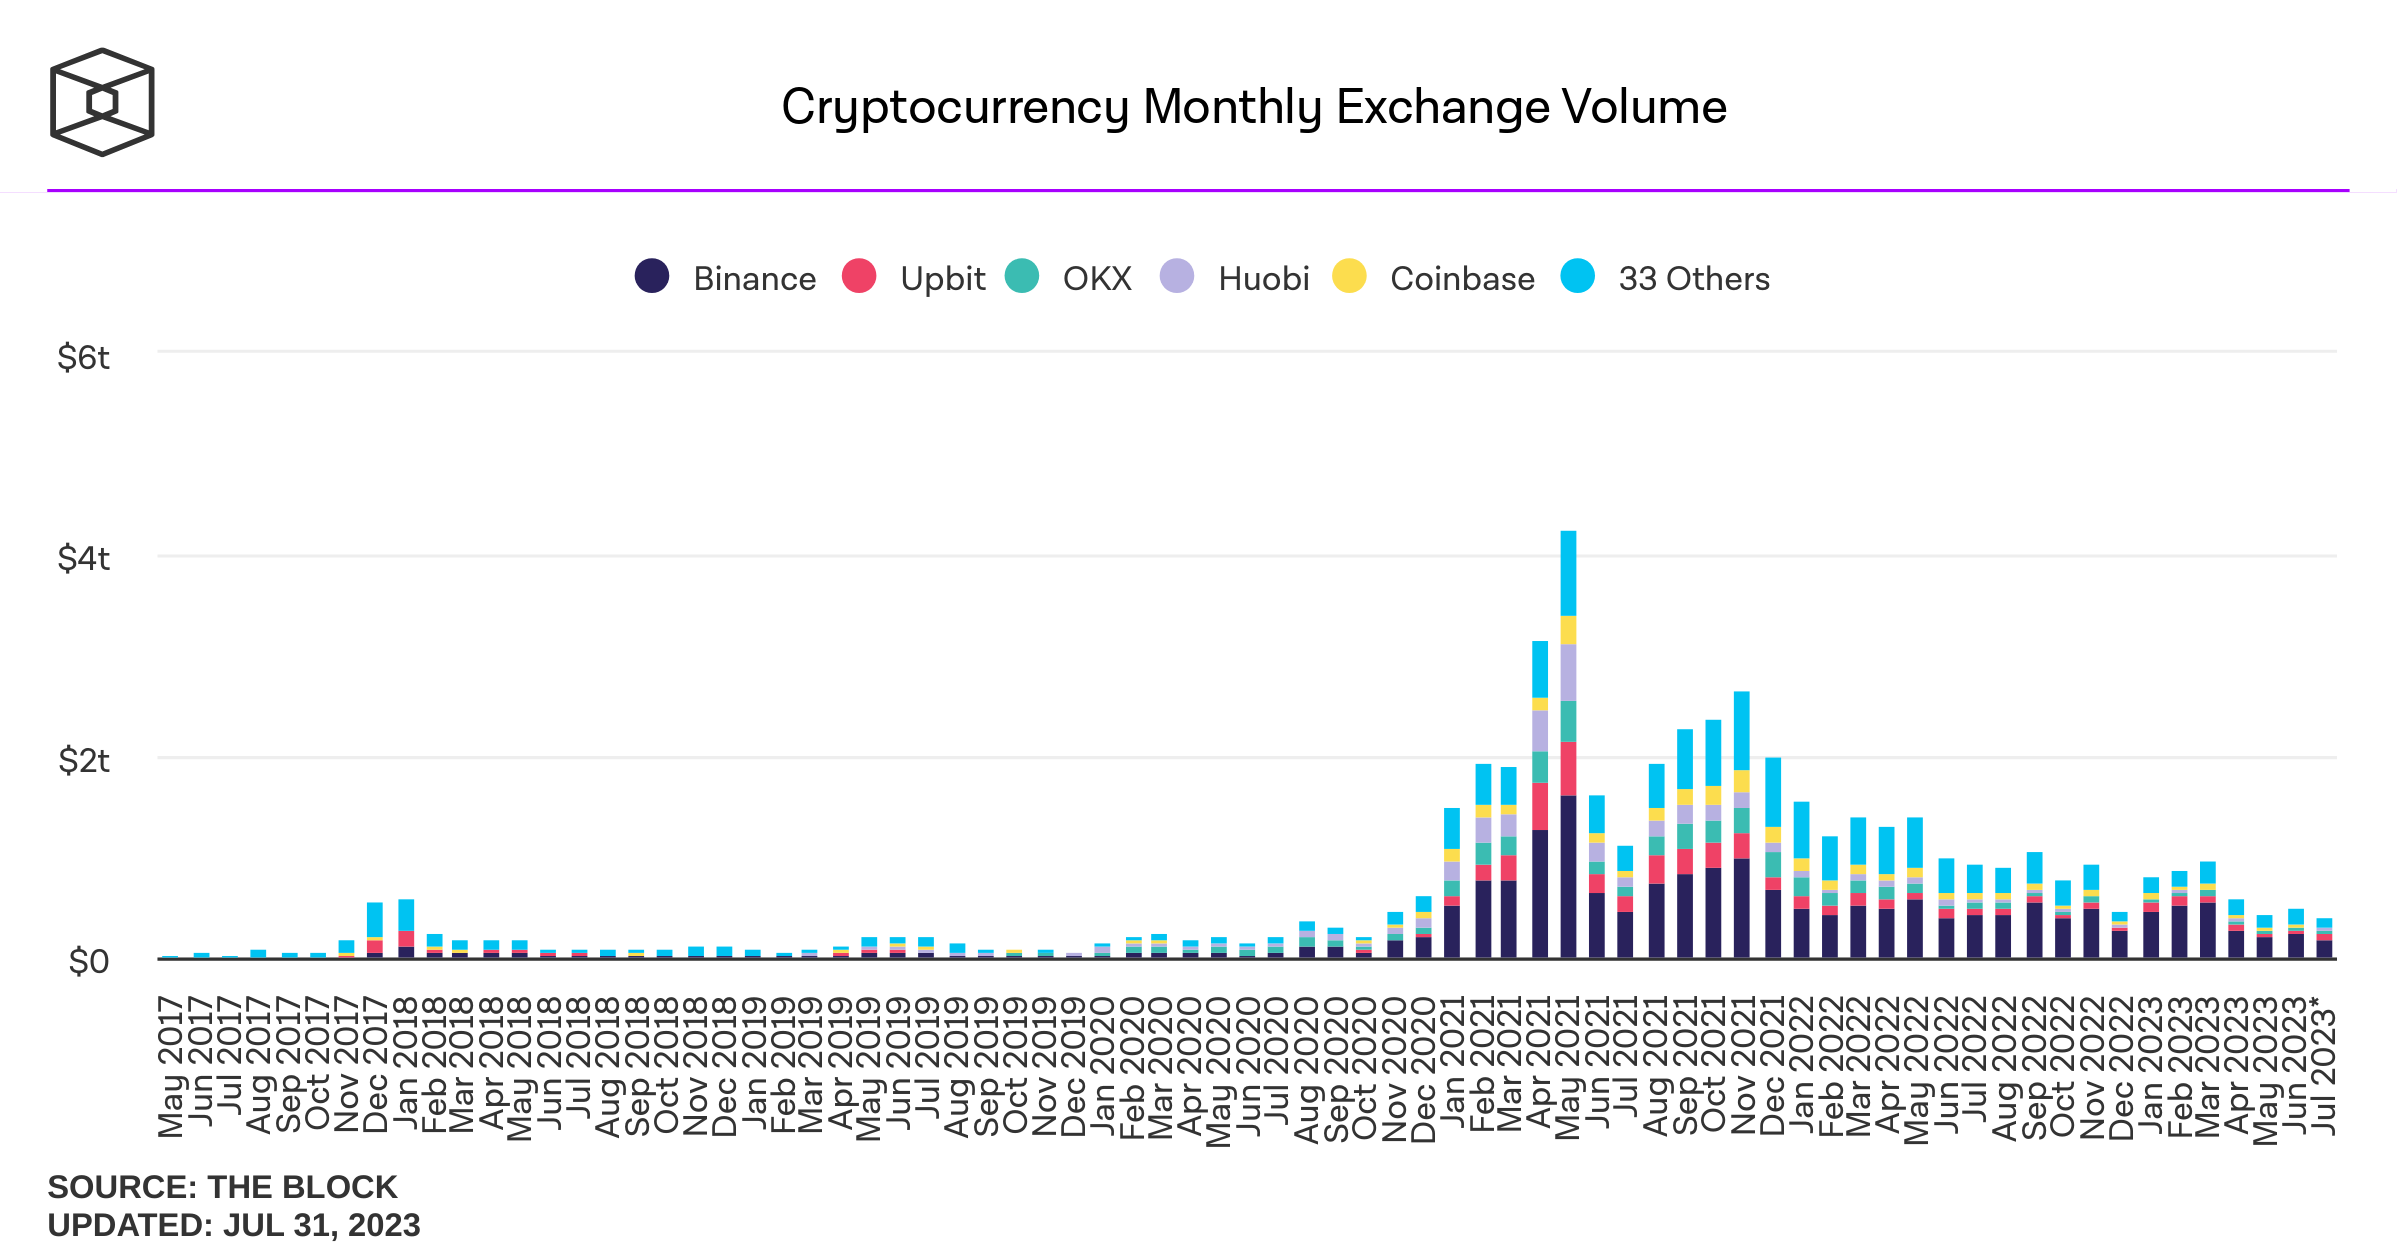
Not everyone is a winner, though. Traders rely on volatility and hence these serene times are not exactly a boon. If we look at spot trading volume, the drawdown has been steep. Granted, there are myriad factors at play here, including regulation, a drawdown in prices, lockdowns ending, scandals (FTX and the SEC lawsuits) and so on, but the lack of volatility is not helping. 

The below chart from The Block shows quite how far spot volume has fallen. 

Even derivatives trading volume, which had been more stout, has fallen off since April – likely a better gauge for traders than assessing spot volume. Liquidity is not as much of a concern in derivatives markets as it has become in spot markets, but the last few months have begun to see some thinning out there, too. 

While the falling volatility is notable, it should be noted that crypto remains a league above trad-fi markets with regard to this metric. Even this three-year low still translates to an annualised volatility of 25% for Bitcoin, which would not be deemed low-risk by any stretch of the imagination. 

To put this up in lights, comparing Bitcoin to gold is always illustrative. Gold is the store of value which has been around for thousands of years, the shiny metal known for its inflation-hedging abilities and lack of correlation to risk assets. For many, Bitcoin’s vision is to claim the title of some sort of digital gold. 

The below chart displays the current gulf between these assets – even after the dampening down in crypto volatility this year, it’s on a completely different planet to gold. 

Alternatively, one can simply compare the daily returns of the assets, which conveys the same thing. 

Thus, while crypto volatility is currently sluggish, it has a long way to go before it matches gold. More importantly, there is no guarantee that this volatility will stay low. Quite the opposite – given the low liquidity in the space, less capital is needed to move crypto markets than has been the case previously. 

In light of this, it feels like the downward trend in volatility (exacerbated in the last couple of months by a classic summer lull in trading) should return. Not to mention the fact that with the interest rate hiking cycle coming to a close, markets could be at an inflection point. It is always hard to predict the future in crypto, but it feels unlikely that digital assets’ volatility will stay at these uncharacteristically low levels for long. 

The post Bitcoin volatility at three-year low as crypto markets lull appeared first on CoinJournal.