Immutable X is down by more than 6% despite TurnerSportsPR partnership

The cryptocurrency market has lost nearly $100 billion over the past 24 hours, with numerous coins and tokens trading in the red zone.  

The cryptocurrency market has been in a bearish trend for the past few months, and things took another negative turn this week. The total cryptocurrency market cap has dropped below $900 billion, down by more than $2.2 trillion from the all-time high attained in November 2021. 

At press time, the total market cap stands below the $900 billion region. Bitcoin and the other major cryptocurrencies have recorded massive losses over the past few days.

Bitcoin is trading just above the $21k support level, while Ether risks dropping below $1,000 if the bearish trend continues. 

IMX, the native token of the Immutable X ecosystem, is down by more than 6% over the last 24 hours. This latest development comes despite Immutable X announcing a major partnership agreement with TurnerSportsPR.

TurnerSportsPR is a leading sports news brand and houses platforms such as Bleacher Report, TNT and TBS. 

Per the terms of the agreement, Immutable X will work with TurnerSportsPR to build blockchain games for premier sports, powered by StarkWare.

Key levels to watch

The IMX/USD 4-hour chart is very bearish at the moment as Immutable X has recorded huge losses in the last few days. 
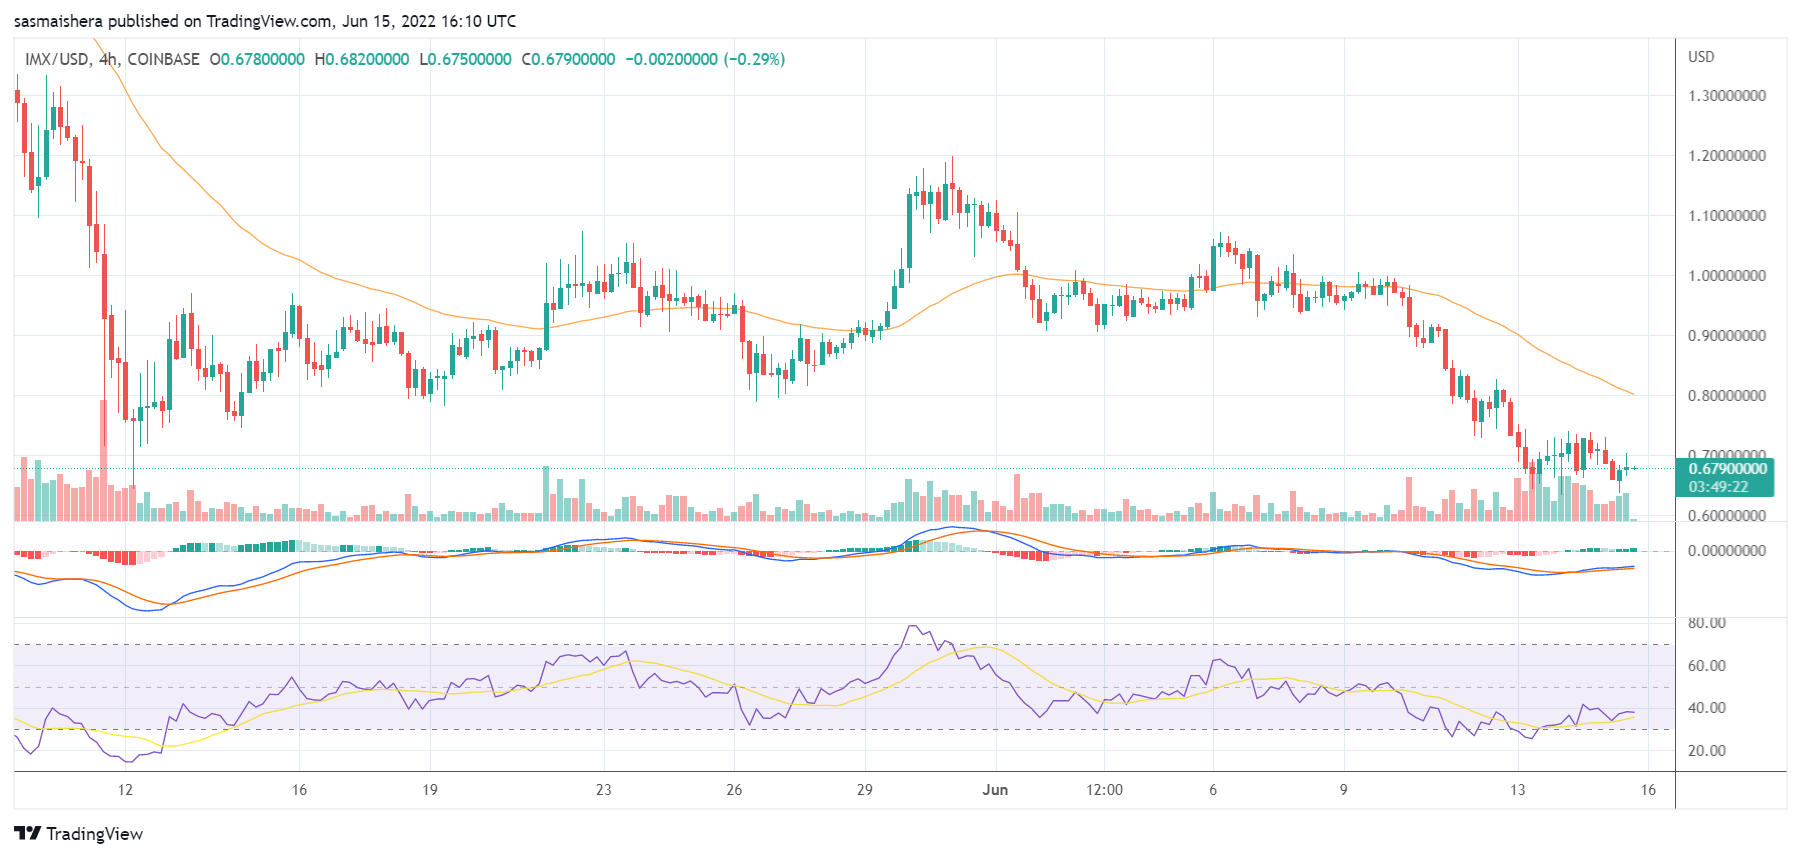
The MACD line is below the neutral zone, indicating bearish momentum. The 14-day RSI of 36 shows that IMX could soon enter the oversold region.

At press time, Immutable X is trading at $0.68 per coin. If the bearish trend continues, IMX could drop below the $0.55 resistance level over the next few hours.

Unless there is a massive selloff, IMX should stay above the $0.50 psychological level in the near term.

The post Immutable X is down by more than 6% despite TurnerSportsPR partnership appeared first on CoinJournal.
Bitcoin recovers above $21k after dropping to the $20k region

The cryptocurrency market has lost nearly $100 billion over the past 24 hours as the bearish trend continues.

The bear market is here, and it is in full motion. The cryptocurrency market has lost more than $2 trillion since the all-time high of $3 trillion was achieved in November 2022.

At press time, the total market cap stands below the $900 billion region. Bitcoin and the other major cryptocurrencies have recorded massive losses over the past few days.

At press time, Bitcoin is trading above the $21k resistance level, down by more than 4% in the last 24 hours.

The cryptocurrency’s performance has improved as it slightly dropped below the $21k level a few hours ago.

Bitcoin’s total market cap has dropped below the $500 billion mark for the first time this year. In November, Bitcoin’s total market cap rose to an all-time high above $1 trillion.

However, the leading cryptocurrency has lost more than 65% of its value since then.

Key levels to watch

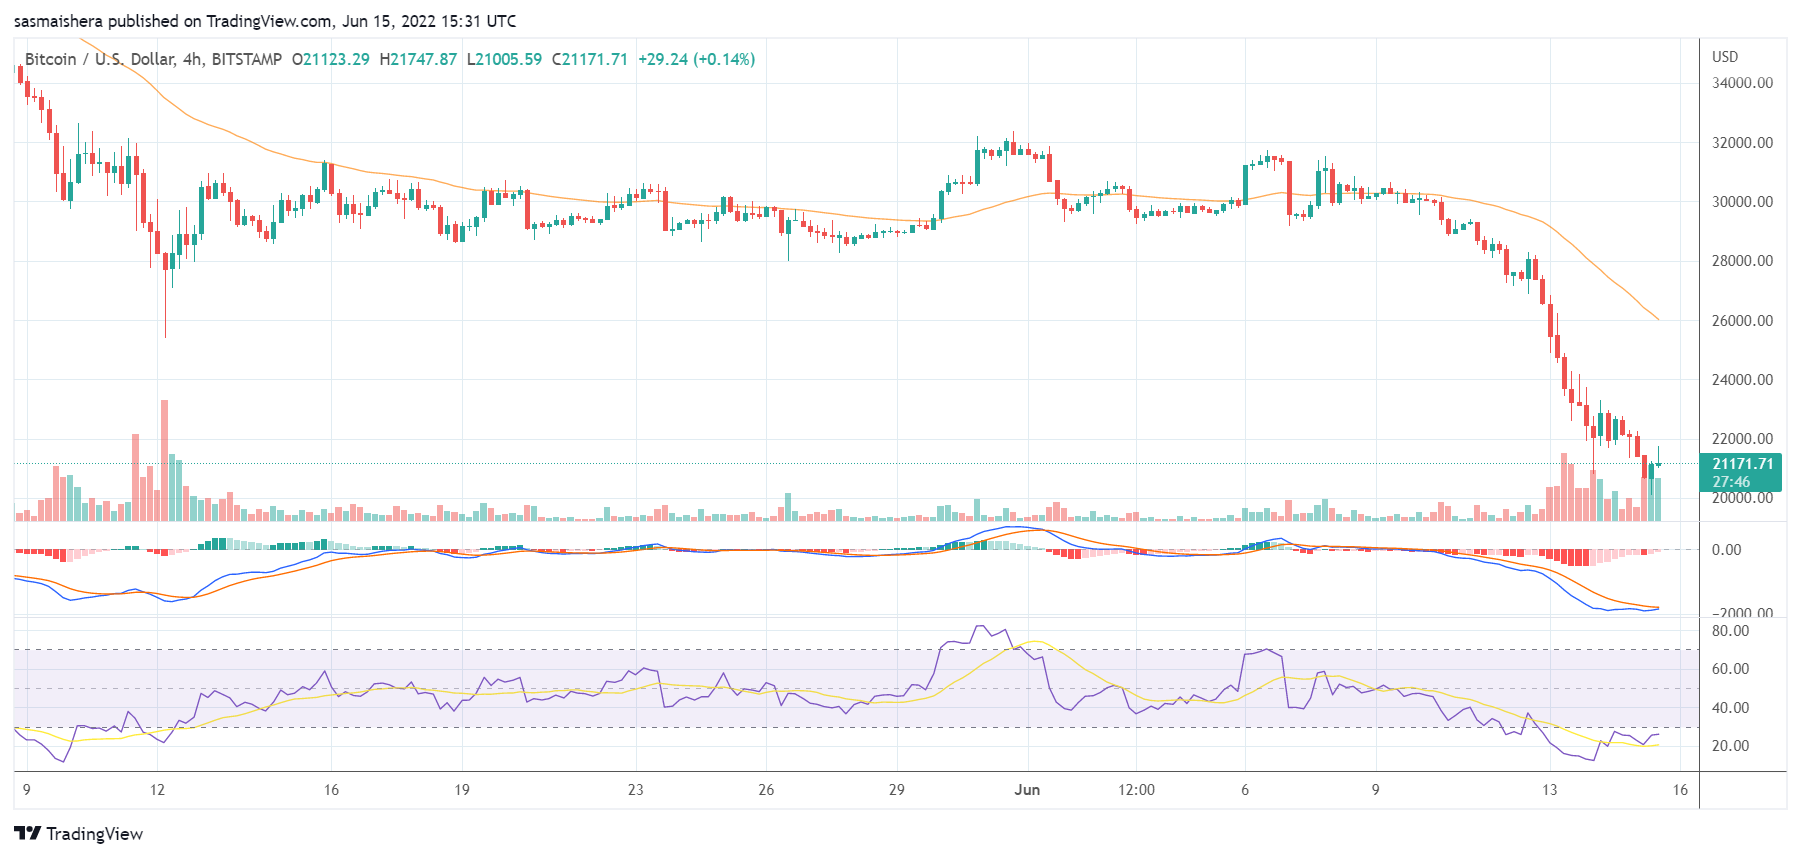
The BTC/USD 4-hour chart is extremely bearish as Bitcoin has been underperforming in recent days. The technical indicators show that Bitcoin could record further losses in the short term.

The MACD line is within the negative territory, indicating an extreme bearish condition. The 14-day relative strength index of 26 shows that Bitcoin is currently oversold.

At press time, Bitcoin is trading around $21,183. If the bearish sentiment grows stronger, Bitcoin could retest the $20k support again before the end of the day. However, the leading cryptocurrency should steer clear of the sub $19,300 support level in the short term.

On the flip side, the bulls could mount a recovery challenge and push Bitcoin past the $22k resistance level over the next few hours. However, Bitcoin could find it tough to surge past the second resistance level at $24,012 before the end of the day.

The post Bitcoin recovers above $21k after dropping to the $20k region appeared first on CoinJournal.

Crypto lender Celsius hires ‘Restructuring Lawyers’: CEL price pumps and dumps

Celsius Network, a renowned crypto lending firm, has hired ‘restructuring lawyers’ amid the current crypto meltdown that has seen the largest cryptocurrency Bitcoin (BTC) lose about 40% over the past week.

Celsius has reportedly hired attorneys from a law firm called Akin Gump Strauss Hauer & Feld LLP to advise on the way forward as its financial woes pile up due to the falling crypto market prices.

The hiring of restructuring lawyers comes days after the crypto lender told its users that it was pausing withdrawals, swaps, and internal transfers because of extreme market volatility.

CEL price pumps and Dumps

Interestingly, CEL, the native token of Celsius Network, is among the cryptocurrencies that have remained green today. At the time of writing, the price of CEL was up by about 51% over the past 24 hours.

However, CEL had pumped to above $1.1 yesterday before dumping to its current price of $0.4819. There are still no concrete reasons as to why CEL is rising especially since this is happening as activities on Celsius Network remain paused indefinitely.

Celsius looking at options amid insolvency rumors

While Celsius is said to be looking for financial solutions from investors, it is also exploring other alternatives including a possible financial restructuring.

Currently, Celsius lends out customer deposits to other users and in return earns some interest. The company manages over $11.8 billion in crypto assets and offers percentage yields as high as 18.63% of crypto deposits.

Celsius’ move comes as lawmakers around the world start exploring what would happen if crypto platforms fail especially now that cryptocurrencies have lost a lot of value. A bipartisan duo of US senators last week proposed a bill aimed at protecting investors in an event that a cryptocurrency exchange files for bankruptcy. The bill seeks to ensure that customers’ digital assets are held in a separate account from a company’s account.

The post Crypto lender Celsius hires ‘Restructuring Lawyers’: CEL price pumps and dumps appeared first on CoinJournal.

Celsius’ crypto woes are being watched by Washington: report

Washington is keenly watching the crypto sector in the wake of crypto lender Celsius Network’s run into liquidity trouble this past week.

The lender, the largest in the crypto industry, announced a pause to all customer withdrawals and transfers on Sunday. On Monday, the broader crypto market suffered a bloodbath that sank major digital assets to price levels last seen in 2020.

The CEL token price fell as low as $0.15 this week, before recovering to hits highs above $0.56. 

The CEL/USD pair has recovered about 70% of the losses in the past 24 hours, according to trading data from CoinGecko.

Stablecoin-targeted regulations

A report by Yahoo Finance published on Tuesday says, the developments around Celsius, and which come hot on the heels of another meltdown catalyzed by the TerraUSD collapse, have the Biden administration on the lookout.

Per the report, lawmakers in Washington are mulling the possibility of extending proposals on stablecoin regulation to the wider crypto market.

Particularly, the feeling is that the President Working Group’s report on stablecoins could be looked at in line with its application across the entire crypto industry.

Focus on exchanges

An unnamed White House official is quoted to have noted that the collapse of LUNA and Celsius’ woes have brought the sector into sharp focus. 

According to the official, the thinking is around ways of ensuring regulators mitigate the risks associated with recent events.

The potential heightening of regulatory attention comes at a time US lawmakers are also looking to place the regulation of crypto exchanges under the Commodities Futures Trading Commission (CFTC).

Among the many regulatory requirements is the restrictions on exchanges regarding lending out customers’ assets. Exchanges are also expected to adhere to liquidity and capital guidelines, as well as hold customer funds separately from the company’s.

The post Celsius’ crypto woes are being watched by Washington: report appeared first on CoinJournal.

Luxury brand Lacoste expands into web 3 with UNDW3

Lacoste, a French-based luxury clothing brand, has launched a new NFT collection as it expands into Web3.

A press release from the firm said the new experience will come via its aptly named UNDW3 (pronounced ‘underwater’).

The community around the brand will use the digital experience to “take ownership” of the firm, according to the announcement.

UNDW3 with the iconic crocodile brand

Lacoste’s NFTs will feature the iconic crocodile, with the total pieces released corresponding to the L1212 polo shirt the fashion brand’s founder René Lacoste invented.

On 6 June, Lacoste launched a Discord server for the NFT, attracting 55,000 people. 30,000 subscribers registered within the first 48 hours, the firm said. The collection went live on Tuesday 14 June, giving fans a chance to mint an underwater NFT.

In total Lacoste plans to launch 11,212 NFTs in the first drop with each NFT priced at 0.08 ETH. 

Apart from the NFTs giving holders exclusive access to the UNDW3 universe, it will also bring together the brand’s customers and fans.

The firm says this is just the first phase of its journey into Web3 and hopes to see further growth over the next few years.

The post Luxury brand Lacoste expands into web 3 with UNDW3 appeared first on CoinJournal.