Bitcoin risks dropping below $20k as the market retraces

Bitcoin continues to trade above $20k per coin but could decline soon if the broader market underperforms further.

Bitcoin, the world’s leading cryptocurrency, is currently trading at around $20,200 per coin. This comes after failing to surge past the $21k resistance level on Tuesday despite adding more than 3% to its value.

The broader cryptocurrency market has retraced after increasing its value by more than 4% yesterday. So far today, the crypto market has lost less than 1% of its value, with the total market cap now around $990 billion.

After failing to move past the $21k resistance level, Bitcoin is down by 1% in the last 24 hours. If the market continues to underperform, Bitcoin could drop below the $20k psychological level for the second time in a week.

Key levels to watch

The BTC/USD 4-hour chart is bearish as Bitcoin has been underperforming over the last 24 hours. The technical indicators show that Bitcoin is retracing after improving its performance yesterday.
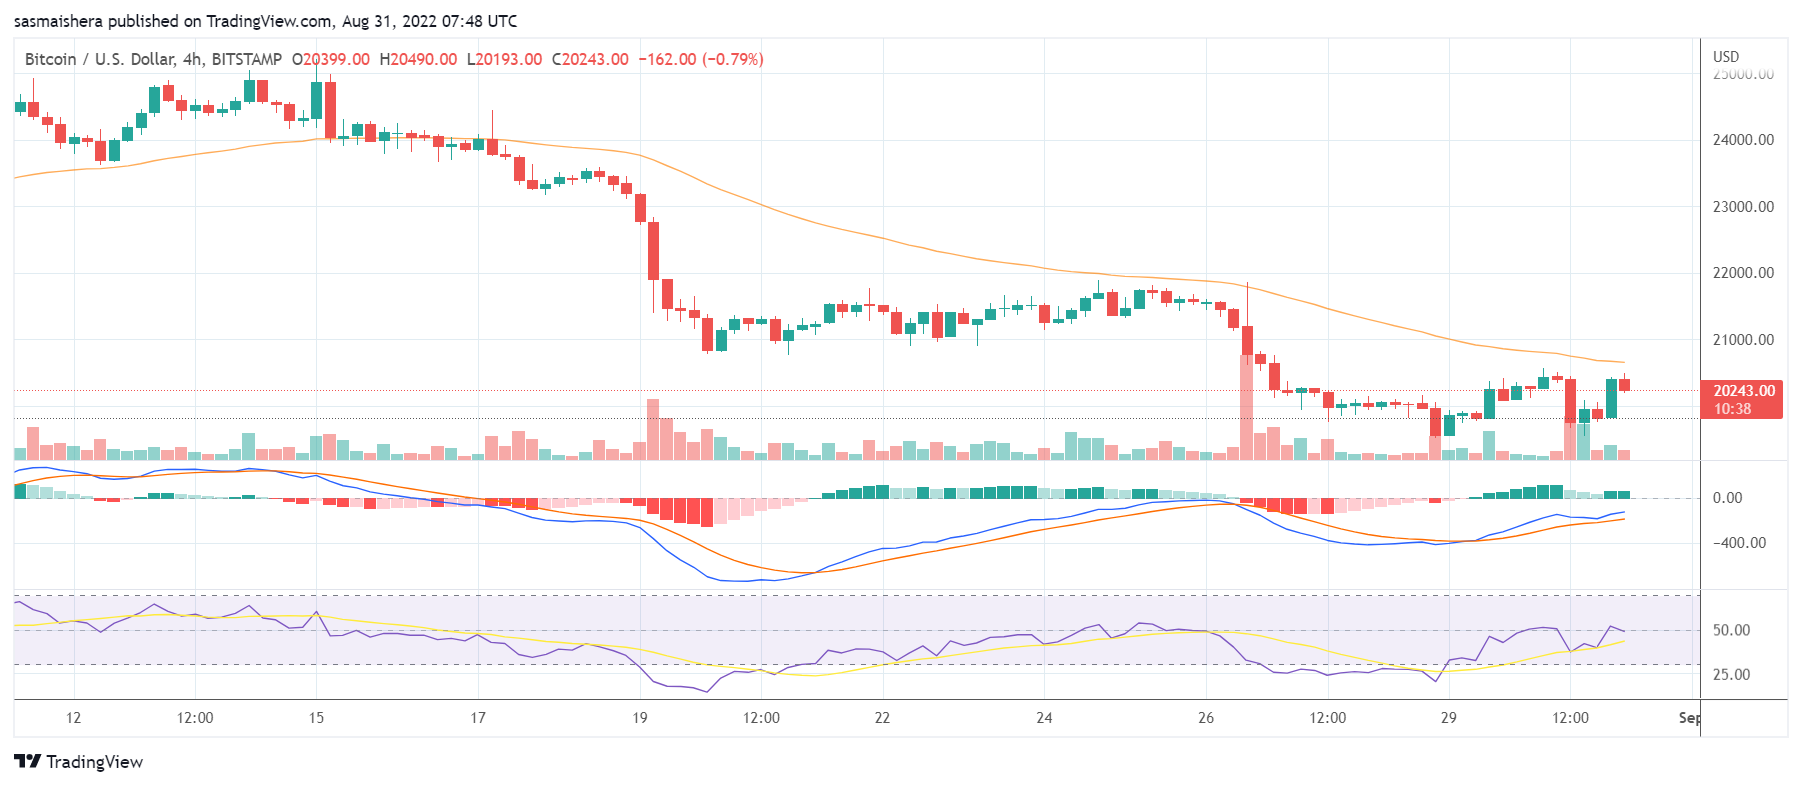
The MACD line dropped into the negative zone on August 25th and has remained there ever since. Thus, indicating strong bearish momentum for Bitcoin.

The 14-day relative strength index of 50 shows that Bitcoin could head down into the oversold region if the bearish momentum continues. 

At press time, BTC is trading at $20,293 per coin. If the bearish trend continues, BTC could drop towards the $19,588 support level before the end of the day. 

Unless the bearish momentum thickens, BTC should maintain its position above the $18,950 support level in the short term.

However, the bearish grip is not tight, and the bulls might still regain control of the market. If that happens, BTC could move past the first major resistance level at $21,059. 

Unless there is an extended bullish performance, the second major resistance level at $22,722 should cap further upward movement in the short term. 

The post Bitcoin risks dropping below $20k as the market retraces appeared first on CoinJournal.
Nexo commits additional $50M to buyback initiative

  • Nexo’s native token NEXO jumped more than 8% as the company announced an additional repurchase plan worth $50 million.
  • The repurchase starts immediately and will continue over the next six months.
  • Nexo completed a $100 million buyback program, launched in November 2021,  in May this year.

Digital assets platform Nexo has committed a further $50 million to its long-standing buyback program after the initiative received backing from the company’s Board of Directors, according to details shared on Tuesday.

The board’s approval allows the crypto lender to make discretionary and periodic repurchases of the native token NEXO, the firm announced.

With the $50 million commitment, Nexo is set to add to the $100 million buyback plan the company launched in November 2021, and which ended in May this year.

“The allocation of an additional $50 million to our buyback plan is a result of our solid liquidity position and Nexo’s ability and readiness to spur on its own products, token, and community, alongside its outward-facing initiatives of injecting liquidity into the industry,” said Nexo co-founder Antoni Trenchev.

The native token NEXO  

According to Nexo, the buyback will be from the open market and starts immediately. The firm also expects the program to continue for the next six months, with all token repurchases going into the company’s on-chain reserve for a vesting period of 12 months.

At the end of the lock-up period, Nexo could use the repurchased tokens to pay daily interest to customers via the native NEXO token. The platform could also use them in strategic investments through token mergers, with the deals incorporating vesting schemes to protect NEXO holders’ interests.

Currently, NEXO price is around $1.04, gaining by more than 8% in the past 24 hours and nearly 17% up over the past week. Despite the crypto bear market, the NEXO token is up by more than 43% over the past month.

So, although NEXO is down more than 70% from its all-time high above $4.00 reached in May 2021, demand for the token looks to be strong across the market.

“In these challenging market conditions, the NEXO Token has moved consistently with the likes of BTC and ETH, demonstrating that, proportionally, demand for our native asset remains strong. Right now, our investors and clients require solid ground to walk on, and our third token buyback ensures this added stability as we emerge from the latest market rollercoaster,” Trenchev added.

The post Nexo commits additional $50M to buyback initiative appeared first on CoinJournal.

Bitvavo adds staking support for SOL, LUNA2, ATOM

Bitvavo now supports staking for three new tokens- SOL, ATOM and LUNA2.

Dutch crypto platform Bitvavo has added three new cryptocurrencies to its staking rewards service.

Now with Solana (SOL), Luna (LUNA2) and Comos (ATOM), customers can leverage their holdings to enjoy staking rewards of up to 10% APY.

Stake SOL, LUNA and ATOM

Staking is one way cryptocurrency holders participate in the network transactions and security of a blockchain network. By locking up their assets for a given period, holders help facilitate the said activities, with a reward earned as part of the incentivisation process.

Bitvavo now supports the above coins, offering a flexible staking feature that allows users to stake or unstake their crypto assets at will.

In their latest update the Dutch-based platform noted the following as the new yearly yield (annual percentage yield, or APY) for the three proof-of-stake digital assets.

Here is what you earn when you stake with Bitvavo:

  • Solana (SOL): earn up to 5% reward
  • Luna (LUNA2): earn up to 6% reward
  • Cosmos (ATOM): earn up to 10% reward

The update means the maximum yearly reward for staked assets on the De Nederlandsche Bank (DNB) regulated platform is higher than the 7.5% initially offered on Icon (ICX).

Users can access and keep tabs on their staked assets in the Bitvavo app.

Cardano (ADA) staking reward update

Apart from adding Solana, Cosmos, and Luna, Bitvavo has updated the staking reward for Cardano (ADA). This has been reevaluated from 5% to 4.25%.

Factors that help determine the yield rate include the average pool rate, blocks per Epochs, amount of ADA pledged and staking costs relating to the percentage of the reward pool operators take.

Bitvavo has over 1 million users and offers up to 180 digital assets, including Bitcoin and Ethereum.

The post Bitvavo adds staking support for SOL, LUNA2, ATOM appeared first on CoinJournal.

Crypto custody and services firm Fireblocks adds support for Solana

The venture-backed crypto custody and services firm Fireblocks has added support for Solana. Fireblocks users will now be able to directly interact with Solana applications on Fireblocks’ platform

The integration allows users to connect and interact directly with decentralized applications (dApps) built on the Solana ecosystem. Developers on the Solana ecosystem will also be able to utilize a wide variety of tools.

Fireblocks CEO Michael Shaulov said:

“Fireblocks’ Web3 Engine offers Solana builders the highest level of security when it comes to accessing the blockchain and its ecosystem of applications for their customers.”

According to DeFiLlama, the total locked value on Solana was approximately $1.4 billion making it the sixth largest blockchain in terms of this metric. In addition, Solana’s non-fungible (NFT) community is the second-most active across all blockchains.

Solana price after the integration

After the news of the integration, the price of SOL, Solana’s native token, surged to a daily high of $33.07. The token had however dropped to $31.12 at press time, registering a drop of 2.62% in the past 24 hours.

Today’s drop has made SOL lose half of the gains it had made yesterday and it has aroused fears of resuming the previous bearish trend that had seen it drop to a low of $30.

The post Crypto custody and services firm Fireblocks adds support for Solana appeared first on CoinJournal.

Ava Labs CEO Gün Sirer terms CryptoLeaks claims as ‘scurrilous lies’

Ava Labs founder and CEO Emin Gün Sirer has termed a controversial report by CryptoLeaks as “an obvious fraud” that “everyone should be able to see right through.”

Gün Sirer says the allegations are disheartening and noted that they have come from “false claims” by Ava Labs’ former lawyer Kyle Roche. According to him, Kyle had lied to one of his potential clients about the nature of what he did for Ava Labs – all in an attempt to impress.

He maintains his company has not engaged in any of the activities as alleged by CryptoLeaks.

“The allegations on this site are categorically false. Ava Labs believes in transparency and facing the world head-on, not through behind-the-scenes dealing or activity,” he said in a statement shared on Monday.

Ava Labs had a ‘secret pact’?

In a recent report CryptoLeaks claimed it had damning “spy video” and whistleblower information that showed how Ava Labs, the firm behind the Avalanche (AVAX) blockchain, had engaged in a conspiracy against its rivals.

According to the site, there existed a “secret pact” between Ava Labs and lawyer Kyle Roche of the Roche Freedman LLP firm. Through this pact, Roche would exploit the US legal system in a “gangster style” approach by bringing targeted lawsuits against Ava Labs and Avalanche competitors.

Some of the alleged lawsuits include those against Solana Labs, Bibox and Dfinity Foundation.

The cases were also meant to have the US Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC) among other regulators distracted, keeping them off Ava Labs’ operations.

It was also alleged Roche was filing cases with the aim of gaining access to sensitive documents from Ava Labs rivals and other crypto industry players. For his role, Roche ostensibly secured 1% of the AVAX supply.

No such underhand tactics

Gün Sirer has hit out at all these allegations, maintaining that his company does not “engage in or support” such underhanded tactics as claimed by CryptoLeaks. Refuting the allegations made in both the report and the video clips, he noted: 

“Neither I, nor anyone else at Ava Labs ever directed Roche in his selection of cases. We do not receive materials or information from him, and we do not entrust our legal affairs to him.”

The post Ava Labs CEO Gün Sirer terms CryptoLeaks claims as ‘scurrilous lies’ appeared first on CoinJournal.