
Blockchain.com executives face court for submitting company records late

  • Nicolas Cary and Al Turnball received a summons from Companies House in May
  • Blockchain.com blamed the late filing on a restructuring of the company and a “significant reduction in the wider group’s workforce”
  • The company filed business accounts for the year ending 2020 in October

London-based Blockchain.com is facing prosecution after two senior executives failed to submit company records on time.

The Telegraph reported that Nicolas Cary, Blockchain.com’s co-founder and president, and operations executive Al Turnball received a summons by Companies House in May.

According to the report, Blockchain.com only filed its business accounts in October for the year ending 2020. However, the legal claims focus is on the company’s delayed filing of accounts for the year ending December 2022.

Blockchain.com blamed the late filing on a restructuring of the company and a “significant reduction in the wider group’s workforce,” which the company said has taken time to stablize.

In its 2020 accounts, Blockchain.com said it had hired legal advisors and was preparing to defend the charges against it.

The case was heard at Cardiff Magistrates Court on September 25 and another hearing is expected on November 26.

A spokesperson for Blockchain.com said:

“Blockchain.com takes seriously our compliance with license and regulatory requirements around the world. We have sorted all necessary documents related to this entirely administrative matter, and are confident it will be closed quickly.”

Established in 2011 by co-founder Peter Smith and Nicolas Cary, Blockchain.com has 37 million verified users, serves more than 200 countries, has over 89 million wallets, and has processed more than $1 trillion worth of transactions. Some of its investors include Baille Gifford, DST Global, and Google Ventures.

The post Blockchain.com executives face court for submitting company records late appeared first on CoinJournal.
APE price surges after Yuga Labs launches ApeChain

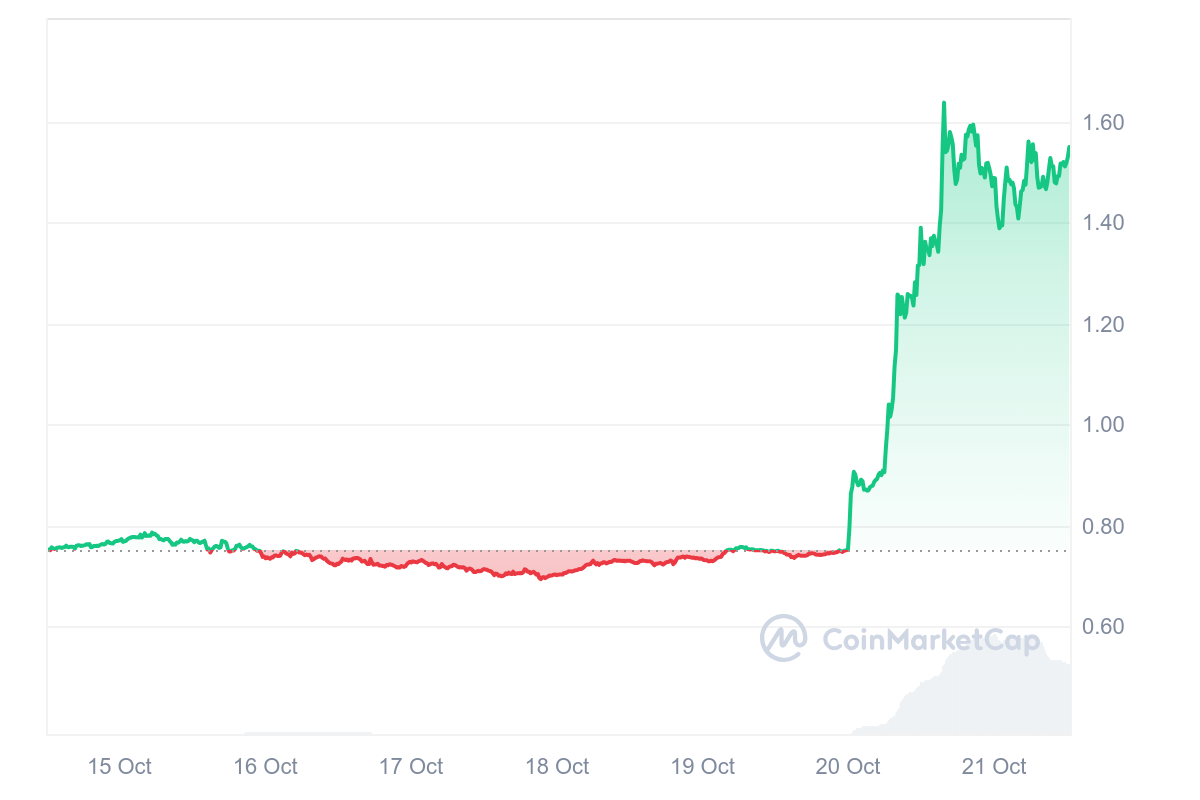
  • APE price reached highs last seen in April, surging more than 15% in 24 hours to break to $1.66.
  • The ApeCoin price was up more than 100% in the past week amid news around the launch of ApeChain.

ApeCoin (APE), the governance and utility token of the ApeCoin web3 ecosystem, rose more to its highest price level since early April.

The APE token, related to the Bored Ape Yacht Club (BAYC) ecosystem, reached intraday highs of $1.66 to see its gains over the past week top 100%. ApeCoin last traded around these levels in April after Bitcoin led cryptocurrencies higher in the rally to above $73k.

Why is ApeCoin price surging?

APE’s gains came as BTC surged to above $69,300 over the weekend. However, there’s another catalyst that looked to have been at play for ApeCoin price.

That’s the launch of ApeChain, a blockchain network offering a layer-3 chain on Arbitrum One. Yuga Labs, the developer of BAYC, announced ApeChain’s debut on Oct. 20.

Horizen Labs and OffChain Labs proposed the launch of ApeChain in December 2023. Debut for the new blockchain network brings NFTs, trading and decentralised applications to APE token holders.

ApeChain bridge is also live, which means holders can transfer APE to ApeChain to earn staking yield. Support includes APE, Ether (ETH) and stablecoins. Meanwhile, integration with LayerZero on the ApeChain mainnet brings the benefits of cross-chain transfers and interoperability to the community.

The APE token traded around $1.53 at the time of writing, about 15% up in the past 24 hours. It reached its all-time of $26.70 in April 2022, which puts the current price about 94% off the all-time peak.

APE price chart on CoinMarketCap

However, APE/USD has surged more than 215% since dropping to lows of $0.482 on August 5, 2024 when most cryptocurrencies crashed alongside BTC.

The potential ascending triangle pattern breakout could nonetheless provide bulls with new impetus.

The post APE price surges after Yuga Labs launches ApeChain appeared first on CoinJournal.

Tap Protocol delays TAP token distribution event

  • Tap Protocol has delayed its TAP token launch date from October 21, 2024 to October 23, 2024.
  • TAP, with a total supply of 21 million, will go live on Bitcoin and Ethereum

Tap Protocol, a decentralized finance platform on Bitcoin, has announced that its anticipated token distribution will now occur on October 23, 2024.

The protocol has earlier announced the Token Generation Event (TGE) would be on Monday, October 21, 2024. However, it released an update early Monday noting that the TGE will now happen on Wednesday, October 23 at 12:00 UTC.

Why the Tap Protocol TGE delay?

According to the Bitcoin DeFi protocol, the postponement is meant to allow ecosystem partners such as bridges to be properly prepared for the potential surge in transactions.

“Nobody likes delays, but unfortunately, we have to postpone our TGE to the 23rd of October at 12:00 UTC. While we understand the wait may be difficult, we want to ensure that our bridge and other products are in perfect condition to support the expected high volume of users,” Tap Protocol posted on X.

TAP will be available on Bitcoin and Ethereum networks at launch, while the roadmap highlights token swap, marketplace and staking as key milestones.

Notable about Tap Protocol is that the TAP token will have a fixed supply of 21 million tokens. The project uses the Ordinals system, with the aim being to advance the BTC ecosystem’s DeFi and dApps capabilities via various assets. It includes non-fungible tokens (NFTs).

The post Tap Protocol delays TAP token distribution event appeared first on CoinJournal.

Stripe acquires stablecoin platform Bridge for $1.1 billion

  • Stripe has closed a $1.1 billion acquisition of stablecoin firm Bridge.
  • The company reestablished support for crypto payments in April, adding USDC on Ethereum, Solana and Polygon in October 2024.

Stripe has completed the acquisition of Bridge, a stablecoin platform that helps companies and businesses accept payments in stablecoins.

According to TechCrunch founder Michael Arrington, Stripe’s deal for Bridge is valued at $1.1 billion and is the fintech company’s largest to date. The TechCrunch founder shared the news via X.

Stripe’s acquisition of Bridge comes after reports of talks for a deal surfaced last week. This also comes after Stripe, which has recently increased its visibility in the crypto space with recent deals such as TaxJar and Lemon Squeezy, unveiled its latest crypto-focused feature.

The ‘Pay with Crypto’ feature, which integrates Paxos, allows companies to add stablecoins to their checkout systems. It’s a step that has also seen several other platforms partner to bring stablecoin payments to more businesses.

Stripe had previously halted crypto payments in 2018 before making a reentry in April 2024. Stripe also partnered with Coinbase to integrate Base, a layer-2 network, in June. In July, the fintech expanded its crypto product to the European Union.

The most recent milestone saw Stripe re-introduce crypto payments with USDC on Ethereum, Solana and Polygon.

Meanwhile, entrepreneurs Sean Yu and Zach Abrams unveiled Bridge in 2022. The platform raised $58 million from venture capital investors, with $40 million secured during a Series A round at a valuation of $200 million.

The post Stripe acquires stablecoin platform Bridge for $1.1 billion appeared first on CoinJournal.