Bitcoin hits 5-month high as bulls push BTC above $23K

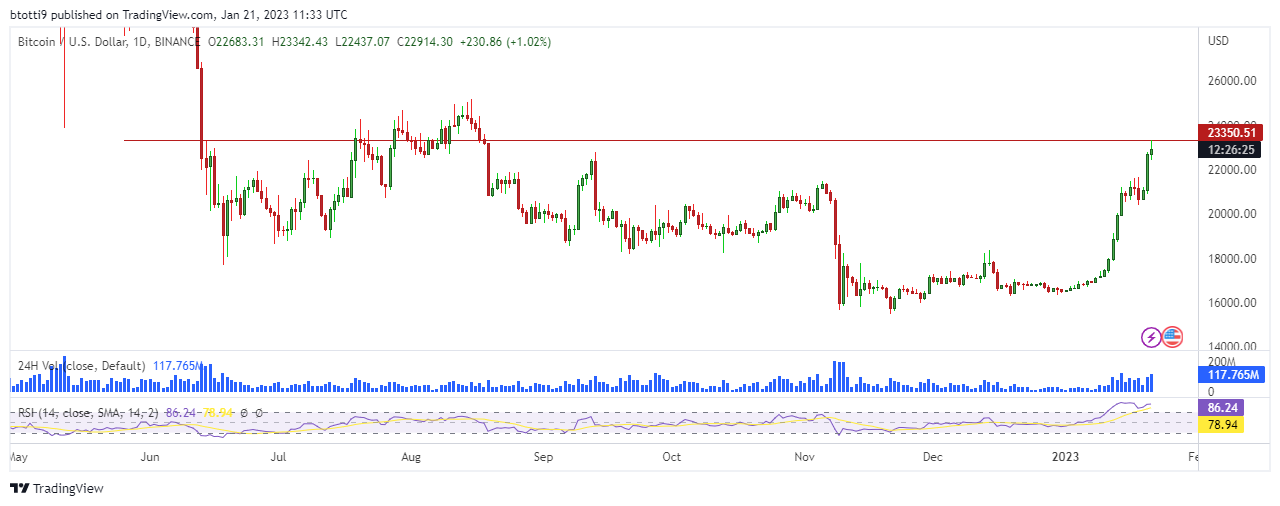
  • Bitcoin hit highs of $23,342 on Binance, with a breakout above $22k extending year-to-date gains.
  • BTC price is up 30% in a month and has recovered 47% since the decline to $15,500 lows.
  • Short liquidations were around $376 million in the past 24 hours.

Bitcoin price roared to highs above $23,000 on Saturday morning, rising to $23,342 on Binance as the price of the world’s largest cryptocurrency by market cap hit levels last seen in mid-August 2022.

BTC was changing hands around $22,900 at the time of writing, about 9% up in the past 24 hours after shedding some of the gains. 

The price of Bitcoin was, however, still 35% up in the past 30 days, and as crypto trader and analyst Rekt Capital pointed out earlier this morning, BTC had rallied over 47% since falling to lows of $15,500 amid the FTX dump.

Bitcoin price chart showing BTC rally to $23,000 on 21 January, 2023. Source: TradingView

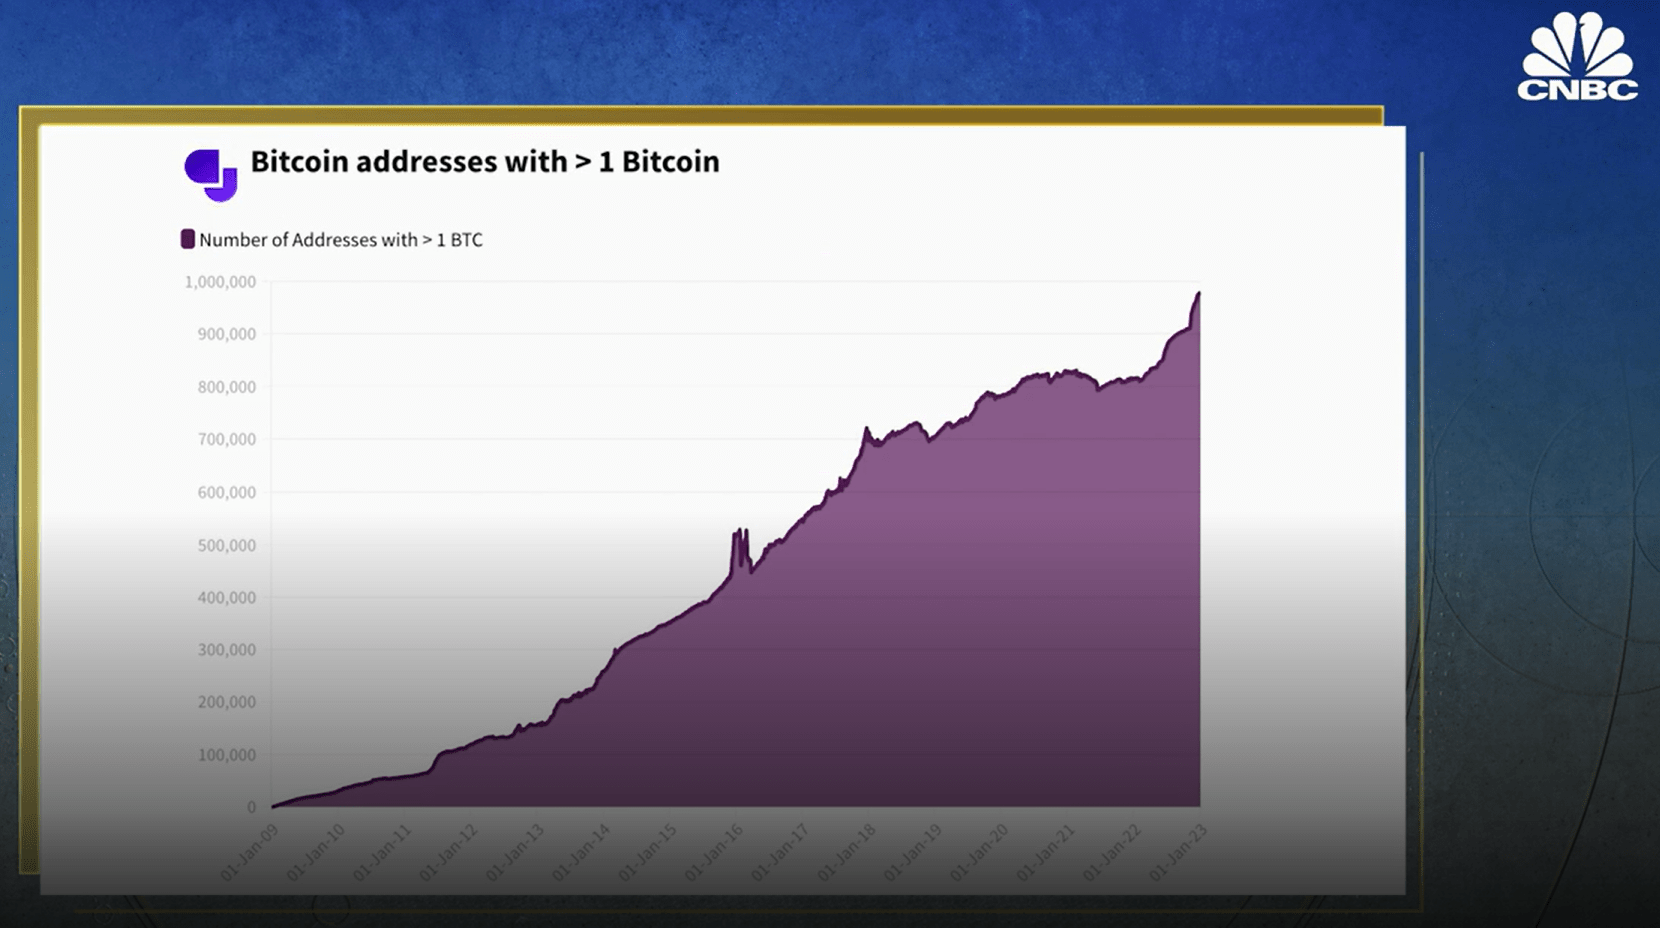
 On-chain data platform Santiment noted just before today’s break above $23k that Bitcoin’s price rally has come amid a bullish outlook from large BTC investors. As the firm highlights in the chart below, whale addresses with 1,000 to 10,000 BTC have in the past two weeks accumulated over 64,638 bitcoins worth more than $1.46 billion.

Over $376 million in shorts liquidated

As Bitcoin raced to highs near $23,350, liquidation data showed that in the past 24 hours, about 80,497 traders had been liquidated.

According to Coinglass, the largest short liquidation was on Bitmex where an order worth $4.53million was rekt. The total liquidations as of 06:10 am ET on 21 January were $376.61 million. 

Notably, total liquidations are not at the levels seen when BTC/USD broke above $20,000 last week towards erasing all post-FTX losses. Nonetheless, it still shows some traders are convinced this could be a gigantic bull trap. 

But as it is, further upside momentum could see bulls target $25,000 or possibly higher if sentiment across risk markets helps bouy buy pressure.

The post Bitcoin hits 5-month high as bulls push BTC above $23K appeared first on CoinJournal.

Bitcoin’s recovery will depend on a lot of macro-activities affecting the market, says Dan Ashmore

  • Coinjournal’s Dan Ashmore says numerous factors, including inflation and rate hikes, have affected the prices of most cryptocurrencies.

  • He told CNBC that Bitcoin’s recovery would depend on numerous macro events affecting the market.

  • Bitcoin and the broader crypto market have lost more than 65% of their value since the all-time high of November 2021.

Bitcoin’s recovery will not happen overnight

Dan Ashmore, a cryptocurrency analyst at Coinjournal, told CNBC in a recent interview that the price recovery of cryptocurrencies will not happen overnight. When commenting about the price collapse last year, Ashmore said;

“Entering 2022, we were at the tail-end of one of the longest and most explosive Bull Runs in recent memory. And then the world is gripped by this inflation crisis post-pandemic. We also experienced one of the swiftest rate hike cycles in recent memories. That sucked the liquidity out of all these risky assets. It is not overly surprising that we have seen this massive pullback.”

The macro climate will play a role in market recovery 

At press time, the price of Bitcoin stands at $21,163, down by more than 60% from the all-time high. While commenting on the possibility of price recovery, Ashmore said the macro climate would play a huge role in that regard. He said;

“In the last month or so, we have seen slightly more positive readings. It still has a long way to go, but it is brighter than it looked a month or two ago. We still have a long way to go before we get back to that $69,000 all-time high. This is not going to be an overnight process.”

He added that the rise depends on a whole range of variables in the macro climate going our way. Furthermore, the avoidance of incidents such as the LUNA, FTX, and Celsius crashes could help boost the market in the long term.

The post Bitcoin’s recovery will depend on a lot of macro-activities affecting the market, says Dan Ashmore appeared first on CoinJournal.

JPMorgan CEO says Bitcoin is ‘a hyped-up fraud’

  • JPMorgan CEO Jamie Dimon previously slammed Bitcoin as a “Ponzi scheme”.
  • On Thursday, he told CNBC’s Squawk Box that crypto is a decentralised Ponzi scheme and that Bitcoin is just “hyped-up fraud.”
  • Dimon says people have lost billions of dollars and believes regulators should have put a stop to crypto “a long time ago.”

Not for the first time, JPMorgan CEO Jamie Dimon has labelled cryptocurrencies worthless.

On Thursday, during an interview with CNBC’s ‘Squawk Box,’ the noted crypto sceptic again referred to Bitcoin as nothing but a “hyped-up fraud.” He condemned the benchmark crypto asset as a “pet rock”, expressing his disapproval by dismissing discussions over BTC and other cryptocurrencies as waste of time.

Dimon says crypto ‘doesn’t do anything’

According to the JPMorgan CEO Bitcoin is not a store of value, and he showed his scepticism further by suggesting that there could be more than 21 million bitcoins in the future.

“How do you know it is going to stop at 21 million? Maybe it’s going to get to 21 million, and Satoshi’s picture is going to come up and laugh at you all. And say ta-da!”

Dimon also went ahead to refer to crypto as a decentralised Ponzi scheme. According to him the hype around digital assets has been extraordinary, stating on the CNBC show:

“You guys, you’ve all seen the analysis on Tether, the analysis on all these things – the lack of disclosures and it’s outrageous. Regulators should have stopped all these a long time ago. People have lost billions of dollars. If you look at its low-income people, in some cases retirees.”

On what he had to say about the crypto industry following the collapse of FTX, the JPMorgan exec summed up his outlook by noting that crypto “doesn’t do anything.”

“It’s a pet rock,” he told the Squawk Box hosts, adding that he doesn’t care about Bitcoin. 

The post JPMorgan CEO says Bitcoin is ‘a hyped-up fraud’ appeared first on CoinJournal.

Bitcoin now at its pre-FTX collapse level

  • At press time, bitcoin (BTC) was trading at $21,507.97.
  • Bitcoin price has surpassed where it stood on November 5 just prior to the FTX collapse.
  • It now stands at its highest price since mid-September last year.

2022 was definitely not a very good year for crypto and especially for bitcoin (BTC) which was trading below $20K for quite a while before the year’s end. Bitcoin had plunged all the way down to about $15,000 in wake of the FTX collapse before attempting a comeback that saw it stuck close to $16,500 for several weeks before embarking on this current rally since the beginning of 2023.

Bitcoin has now corrected the price dip that was caused by the latest crypto misfortune, the FTX collapse that took place at the beginning of November. Early this morning, the price of bitcoin surged to a daily high of $21,564.50 before slightly pulling back to $21,507.97 at the time of writing.

What is behind today’s BTC price surge?

While the general cryptocurrency market is on a bullish trajectory, today’s sudden surge in bitcoin price is largely attributed to this morning’s larger-than-expected decrease in the Producer Price Index (PPI) for the just concluded month of December. The retail sales in December also dropped way below their forecast.

December’s PPI dropped by about 0.5% bringing the year-to-year rate down from 7.3% to 6.2%. The year-over-year rate dropped by about 5.5% against a forecast of a drop of 5.7%.

On the other hand, December retail sales dropped by 1.1% against a forecast drop of 0.8%. Combined with the decline in November, this marks the first time retail sales have dropped back-to-back by more than 1% post the pandemic.

The post Bitcoin now at its pre-FTX collapse level appeared first on CoinJournal.

Half a billion dollars of short sellers liquidated in biggest crypto rally in 9 months


Key Takeaways

  • The cryptocurrency market cap is back above $1 trillion following the biggest surge in 9 months 
  • Half a billion dollars of short sales were liquidated over the weekend, the most in three months
  • Bitcoin is back above $21,000, Ethereum above $1,500, while altcoins have soared
  • Despite powerful bounce, the market is still down close to 65%, having peaked at nearly $3 trillion in November 2021
  • Bear market drawdown at 77% for Bitcoin, but traders are wary this may only be a short-term relief rally

For a few hours over the weekend, if you looked at a crypto chart, it felt like it was 2020 again.

COVID may be fading into the rear-view mirror, but so had crypto prices. I produced a deep dive into some on-chain data last week which showed how torrid 2022 had been for investors, with 73% less bitcoin millionaires, a drawdown of $2 trillion in the overall crypto market, and a reputation dragged through the mud by various scandals. 

Looking at data this week for coinjournal.net, it is a little more optimistic for crypto investors. 

Half a billion dollars of short sellers liquidated

The weekend brought a little respite, however. Bitcoin surged to its strongest rally in 9 months, taking the market by surprise and breaking upwards above $21,000. 

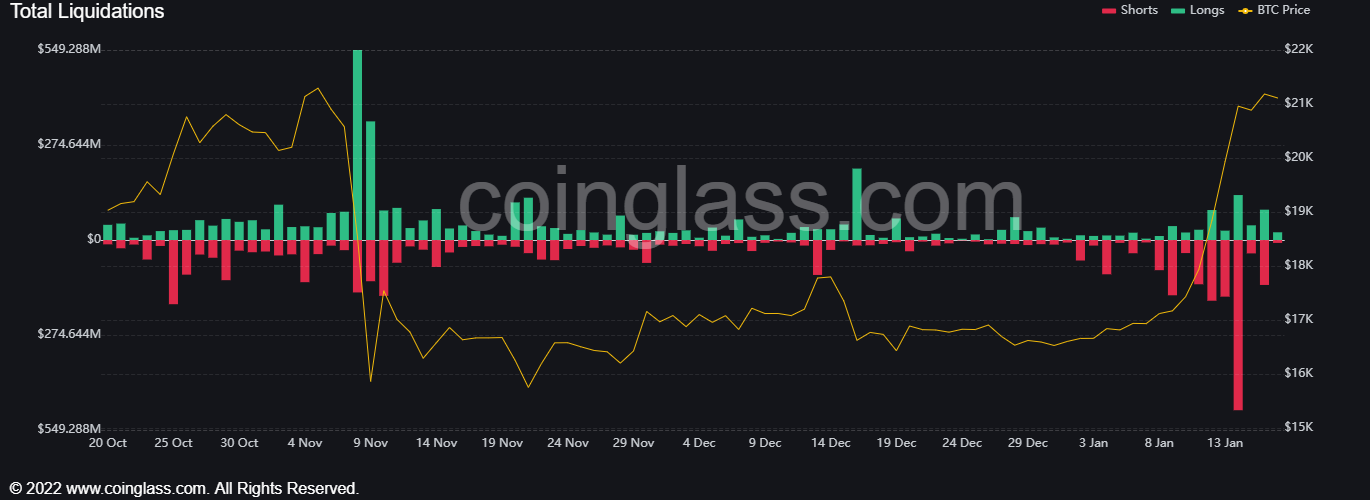
Looking at data from Coinglass, there were over half a billion dollars of short sellers liquidated this past weekend. The below chart shows the extent of these liquidations, more or less matching the long liquidations back when FTX collapsed in early November. 
Crypto market regains $1 trillion mark

The bounce in digital assets followed softer-than-expected inflation data. This optimism that inflation may have peaked has caused investors to bet that the Federal Reserve may pivot off its high-interest rate policy sooner than previously expected. 

As we know by now, high-interest rates have sucked the liquidity from the market, hurting risk assets across the board. Crypto is very much trading like one of these high-risk assets, and hence prices have collapsed as the Federal Reserve has implemented this tight monetary policy – and hence crypto exchanges have been less than kind to long traders. 

2023 has brought hope that if inflation truly has peaked, a light at the end of the tunnel may be visible. The crypto market has surged to regain a $1 trillion dollar market cap as a result. It is still a far cry from the near-$3 trillion all-time high, but Bitcoin at $21,000 and Ether at $1,500 marks the highest prices for the duo since before the FTX scandal. 

Has the crypto market bottomed?

The glaring question facing investors now is whether this is merely a short-term relief rally, or whether the bottom is in. 

As with most questions in the market, macro holds the key. 

“The last couple of months have undoubtedly brought indicators of a more positive environment with regards to inflation, as well as the boost of the Chinese economy reopening,”  said Max Coupland, Director at CoinJournal. 

“However, I do worry whether investors are jumping the gun by presuming that this means the Fed will now pivot sooner than expected. (Fed chair) Jerome Powell has been adamant that rates will not taper until inflation is firmly under control, and we are still a long way from the 2% target, while uncertainties such as the Russian war in Ukraine still loom as highly unpredictable”. 

Let’s play the (very) hypothetical game of assuming the bottom is in. That would put the bear market at 13 months long, with a 77% drawdown from peak-to-trough for Bitcoin. 

Historically, this would place it as the third biggest drawback in history. However, that would only be in percentage terms. The crypto market today is vastly different to years past, and the size of the capital wipeout is on a different level – or over $2 trillion, to be precise. 

So, while the length and size of the bear market could perhaps imply we are in the latter stages, past data simply cannot be reliably extrapolated when it comes to crypto. Bitcoin only broke through as a mainstream asset in the last few years, and prior time periods featured low liquidity and a niche set of investors. 

Today, we are also facing an unprecedented macro climate – rampant inflation, high interest rates for the first time in Bitcoin’s history, and a bear market in the wider economy for the first time since the 2008 crash – the same year Bitcoin was invented. 

In wrapping up, the past weekend has been a welcome reprieve for crypto investors, and amounts to the most powerful surge in nine months, back before the collapses of LUNA, Celsius, FTX and the transition to high interest rates in the board economy. 

But the road ahead remains tough for the market at large, with inflation still lofty, a war ongoing in Europe and myriad other macro variables oscillating. This week has been good news, but crypto investors won’t be counting their chickens quite yet. 

The next mark on the calendar? The all-important FOMC meeting on February 1st, when the Federal Reserve will decide upon the latest interest policy. 

If you use our data, then we would appreciate a link back to https://coinjournal.net. Crediting our work with a link helps us to keep providing you with data analysis research. 

Research Methodology

Liquidation data via Coinglass. Price data from Yahoo Finance. All other data via CoinJournal

The post Half a billion dollars of short sellers liquidated in biggest crypto rally in 9 months appeared first on CoinJournal.